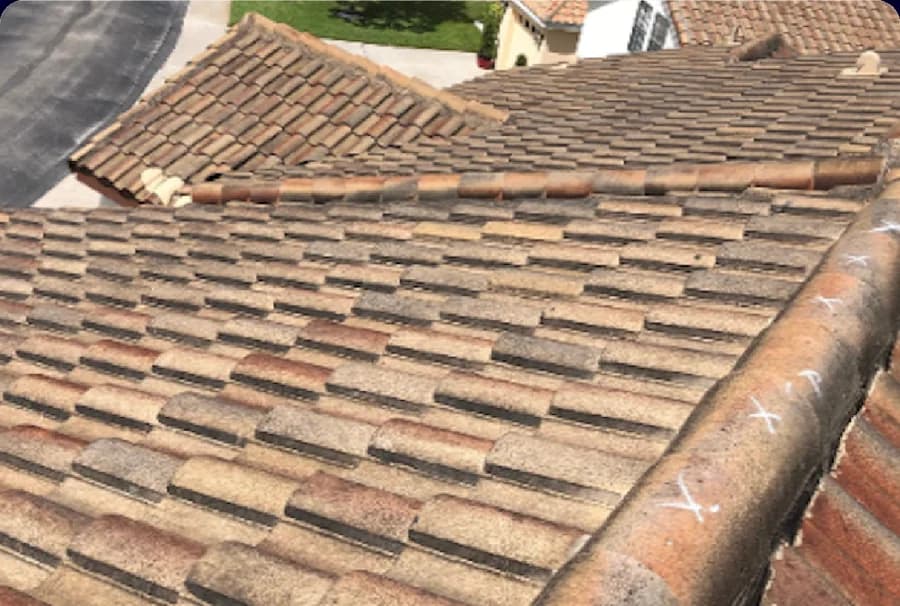
Altamonte Springs, FL
Hurricane
- Initial insurance offer
- $0 - Denied
- Settlement with Five Star
- $2,000,000
Denied to $2M
Commercial Claims Division
Not every public adjusting firm can handle commercial losses. We can.
We work alongside property owners, management teams, and investors to navigate complex insurance claims from start to settlement.
Proven Track
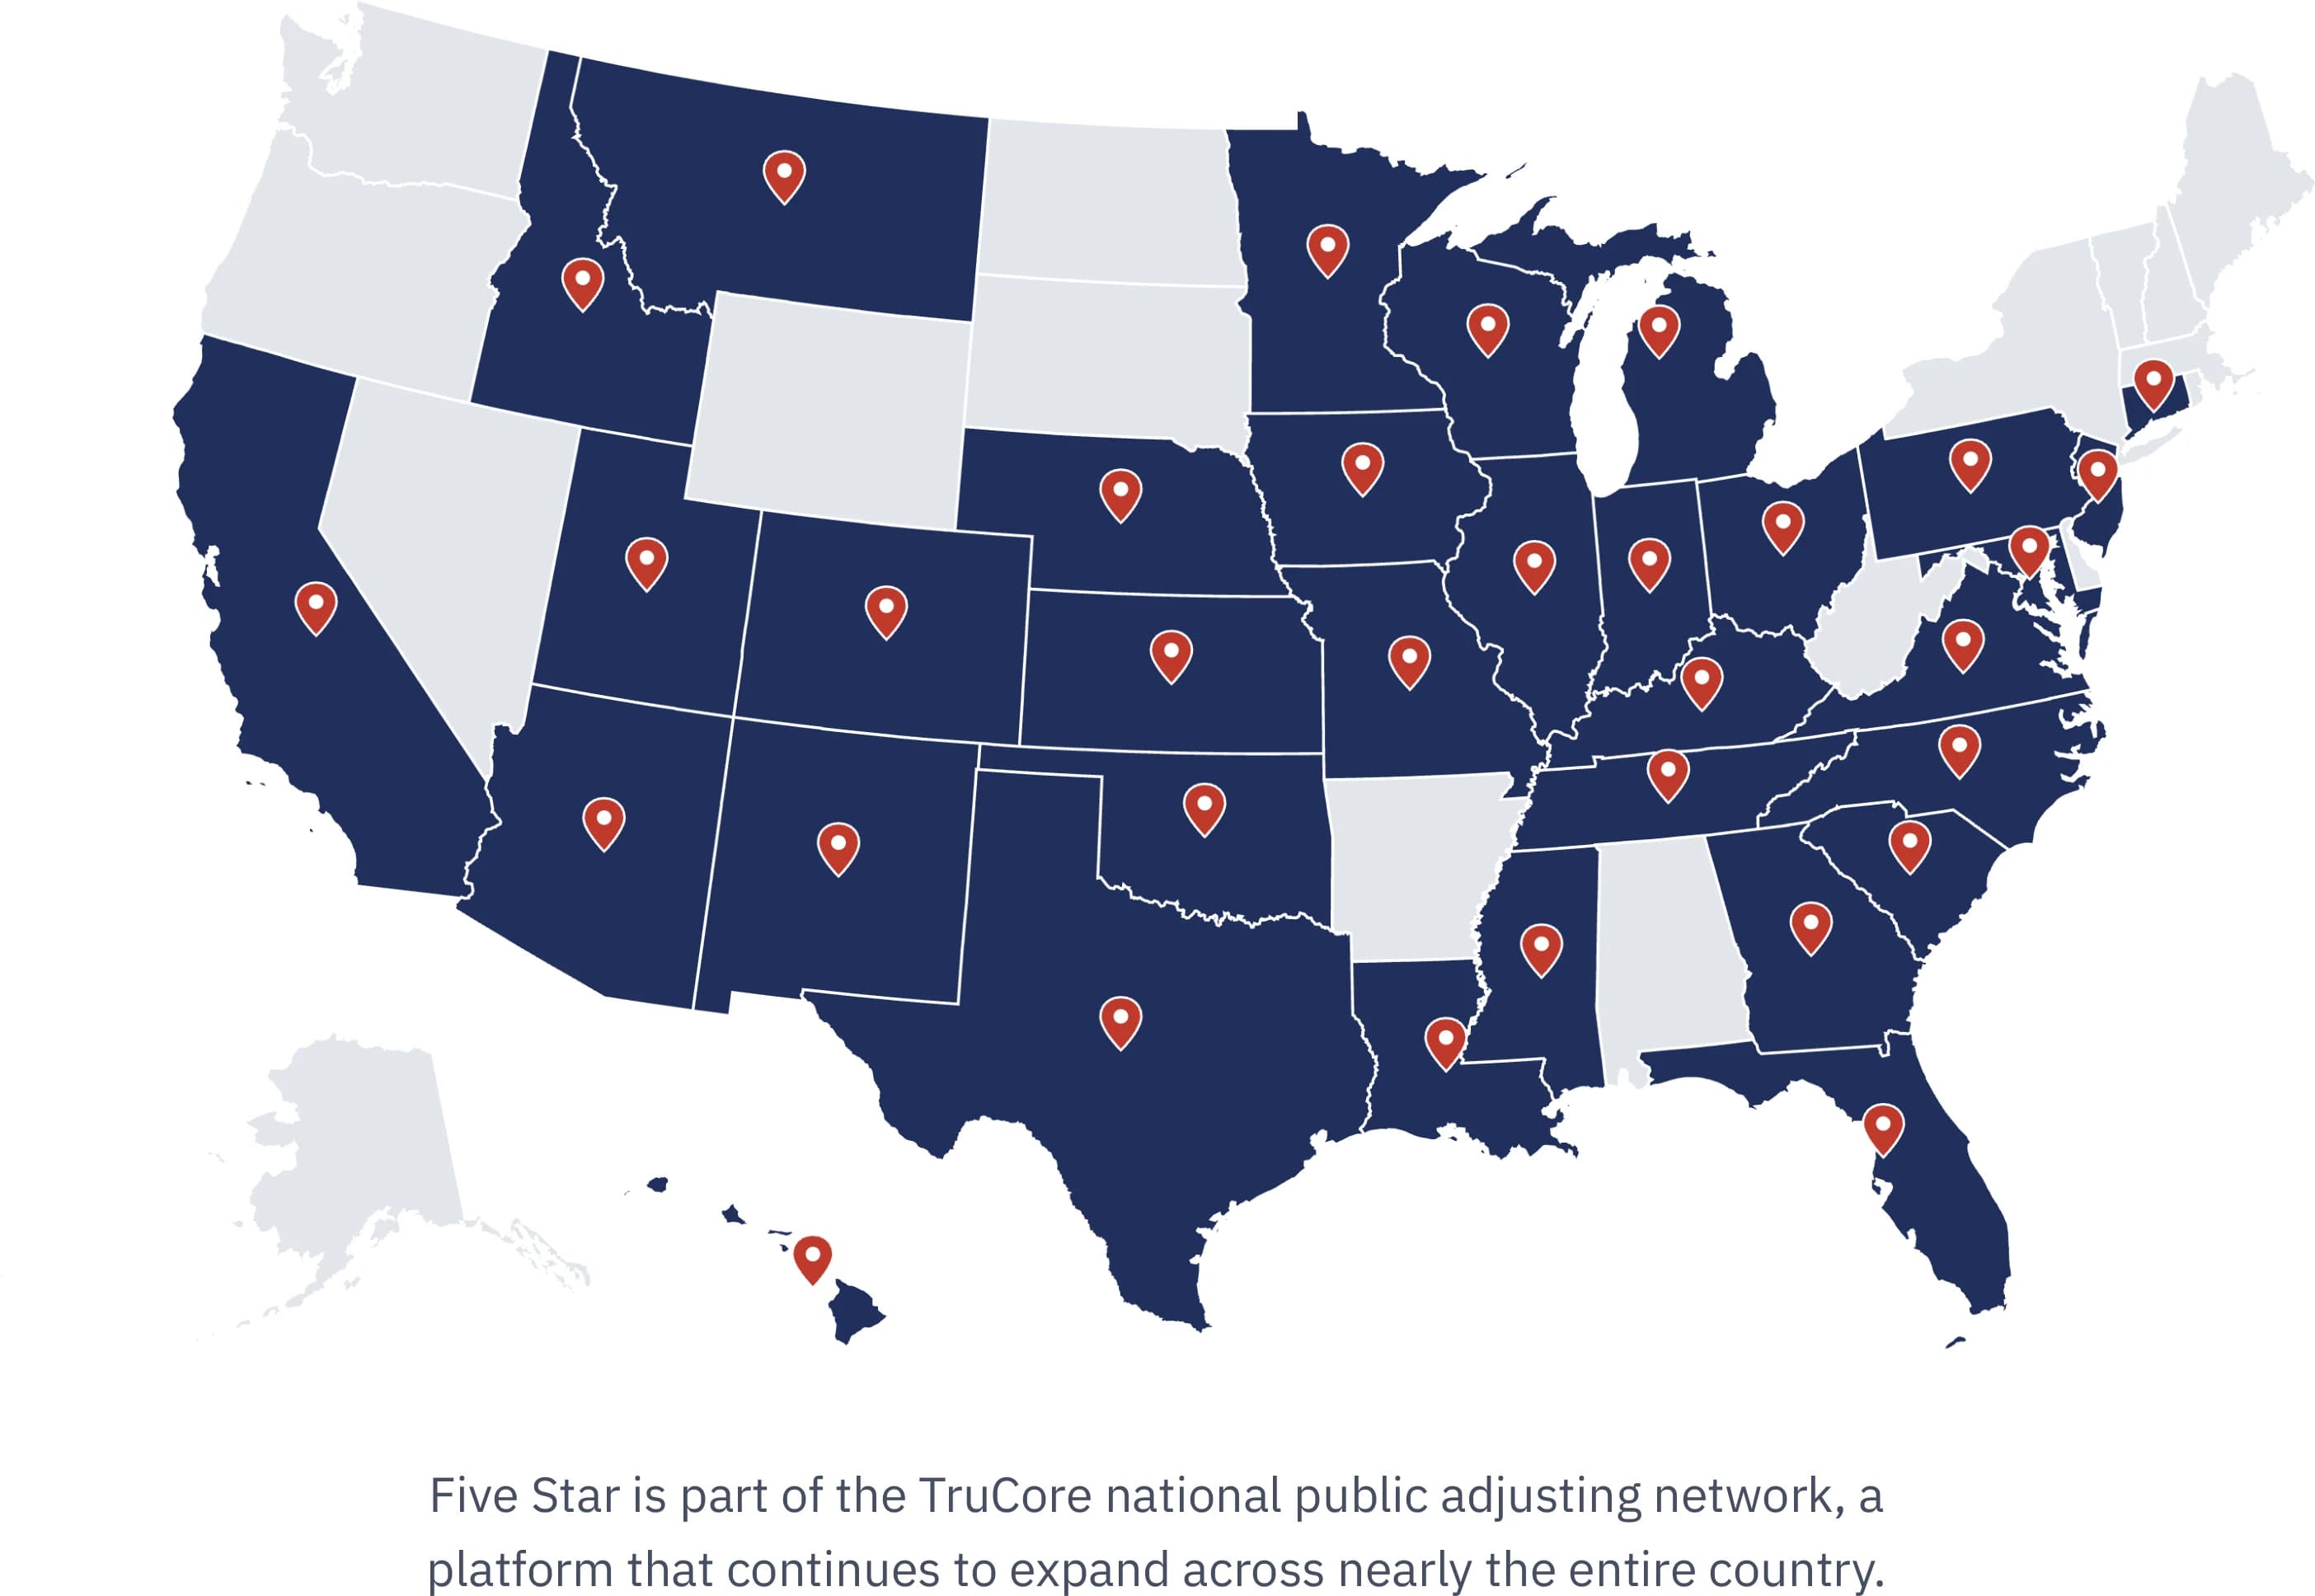
Areas we serve
Carrier's opening position, compared to Five Star's final recovery. Actual commercial settlements.
Hurricane
Denied to $2M
Hailstorm
1MM%+
Wind / Hurricane
5,400%+
Wind & Hail
2,300%+
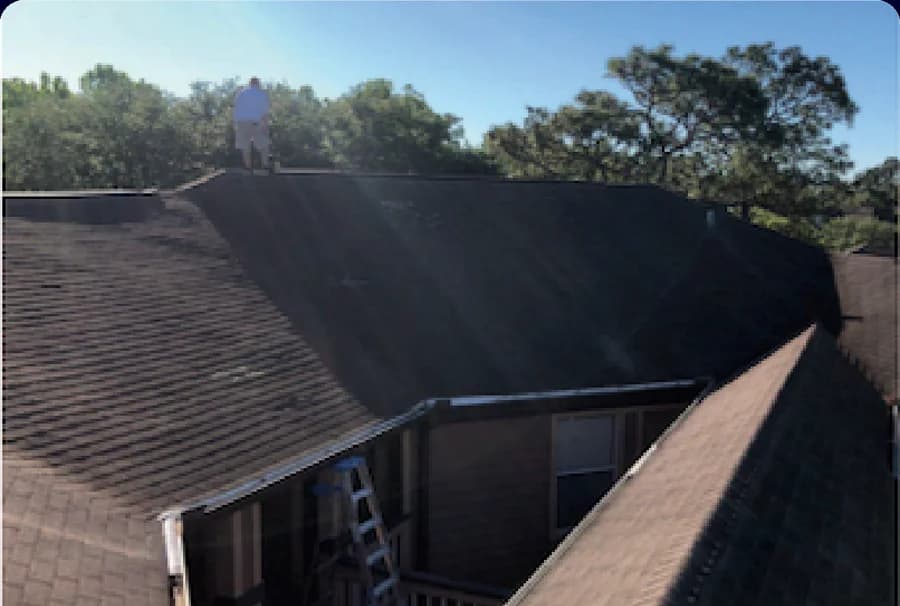
Wind Damage
3,400%+
Hurricane
27,000%+
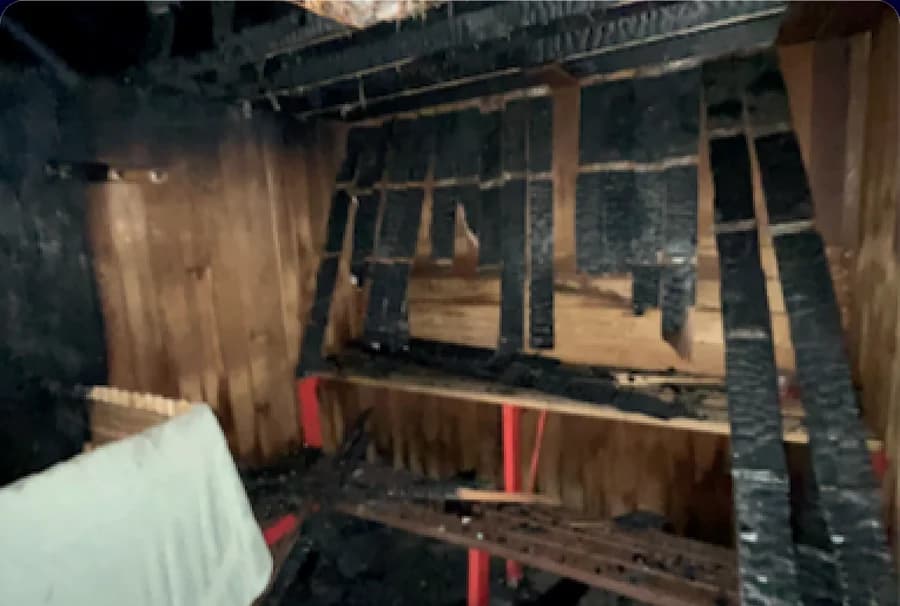
Fire Damage
185%+
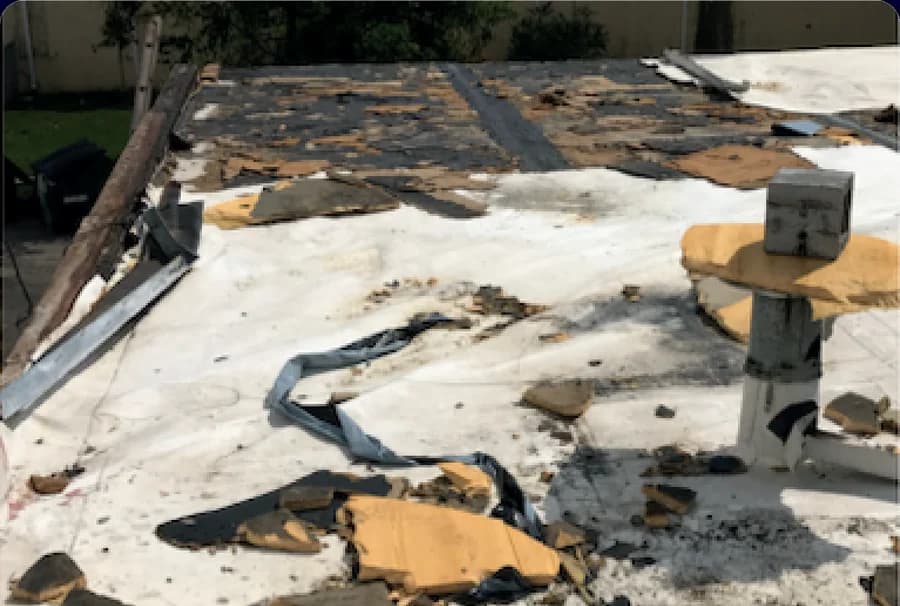
Wind / Hurricane
480%+
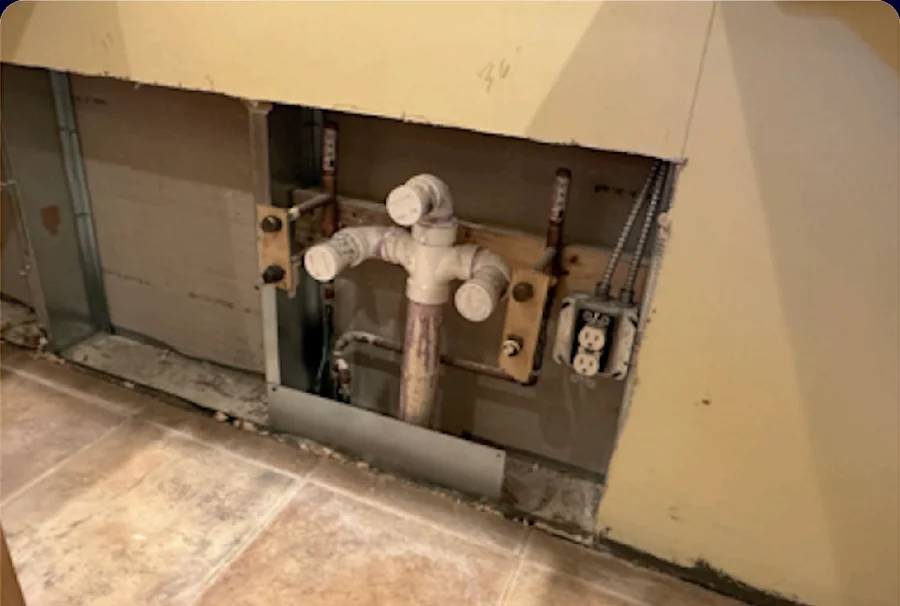
Water Damage
550%+
Actual commercial settlements handled by Five Star. Every claim is different, and past recoveries are not a guarantee of the outcome on any future claim.
The people behind every commercial recovery, from first call to final settlement.
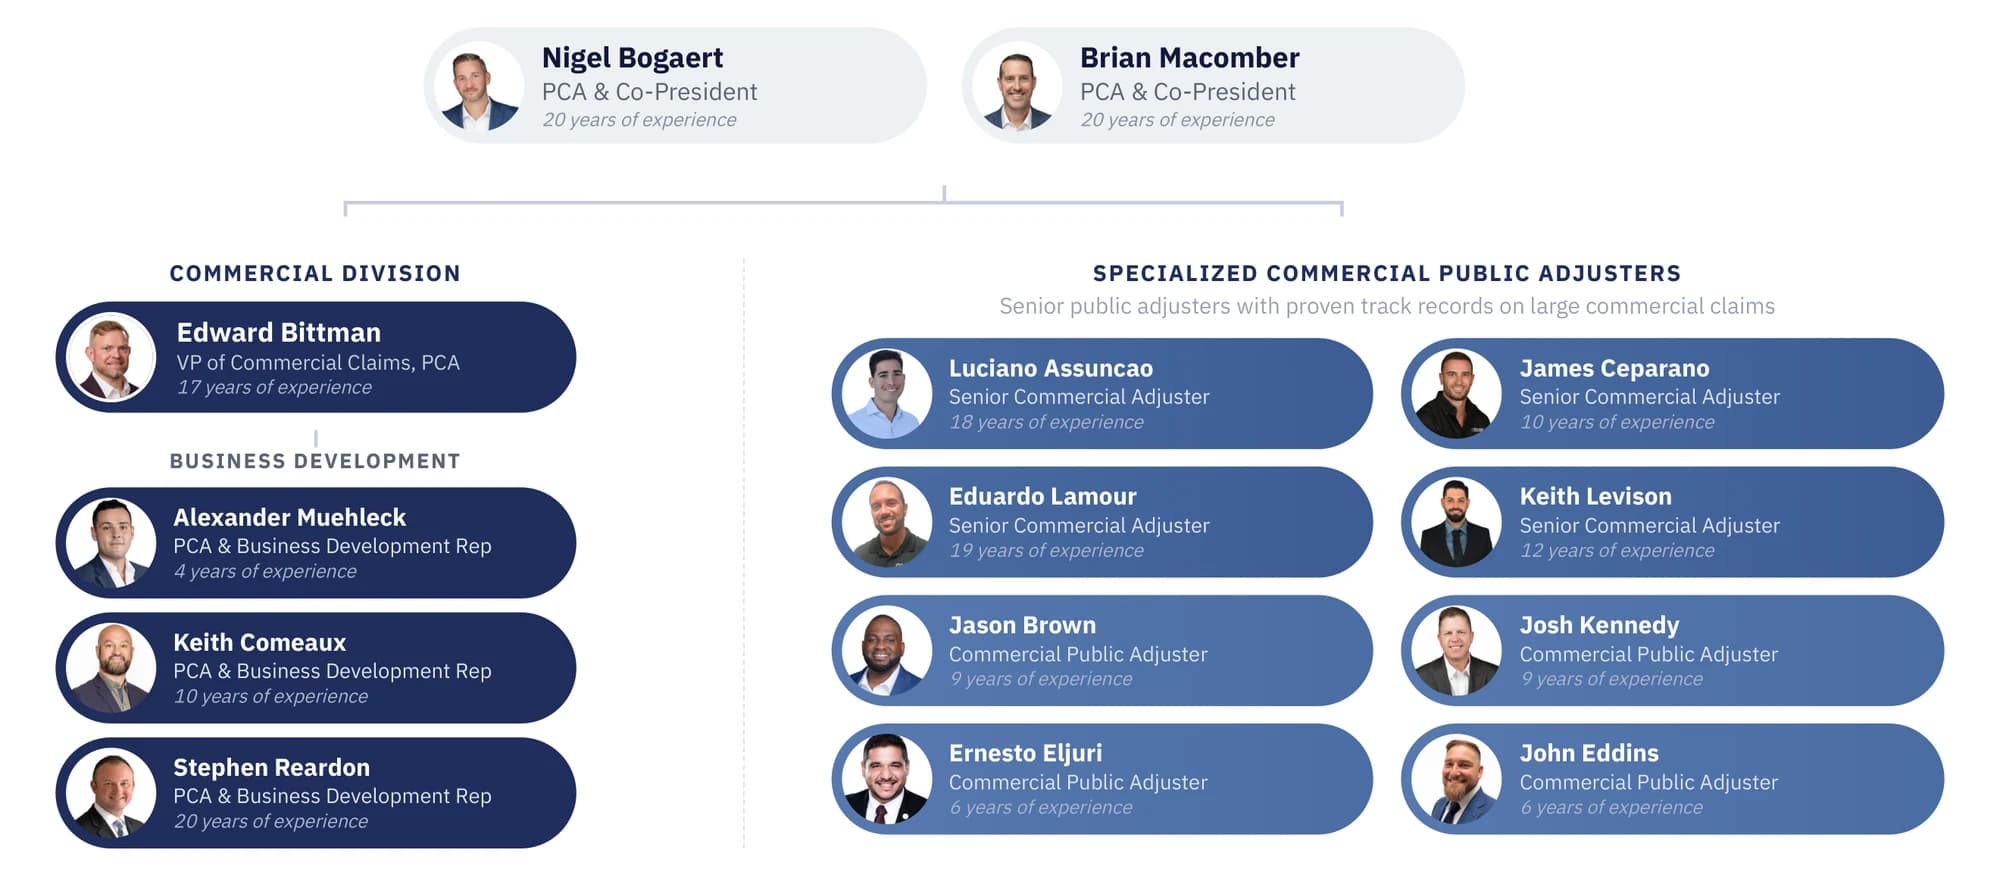
A Commercial Claim Has So Many Moving Parts.
A commercial claim involves more people than most owners realize. Five Star sits at the center of all of it.
On large losses, expect competing experts on both sides. The carrier brings its own engineers and forensic accountants, and so do we. That means your side of the claim is just as well-represented as theirs.
Most public adjusters show up after the damage. We believe the best time to build a relationship is before you ever need to file.
We partner with the professionals responsible for protecting and managing commercial properties across multiple states.
Commercial-scale expertise across every kind of loss.
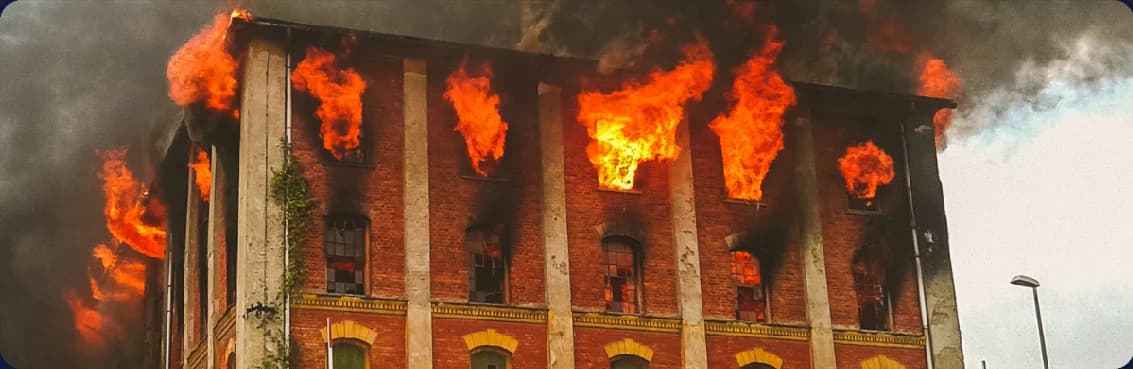
Fire losses rarely end with the flames. Smoke, soot, and water from suppression efforts extend the damage far beyond what's visible. We document the full scope, including the structure, contents, and business income, to recover the full cost of the loss.
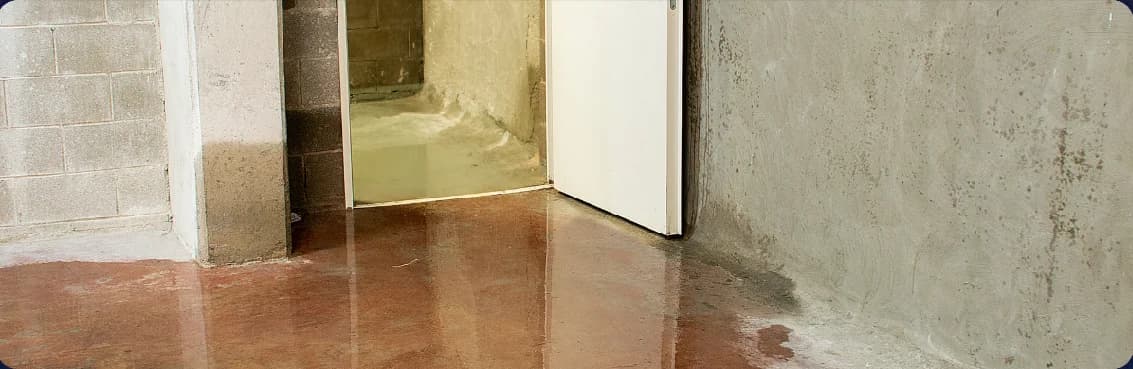
Water spreads fast and hides behind walls, ceilings, and flooring long after the source is fixed. We make sure every affected unit, common area, and hidden pocket of damage is properly documented and covered.
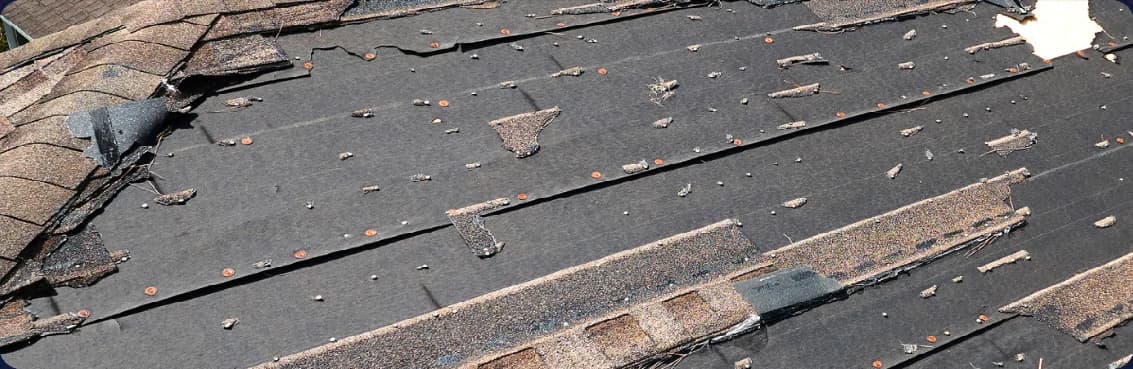
Wind, rain, and flooding often strike the same property at once, and carriers frequently dispute which peril caused what. We untangle that complexity to build a claim that reflects the true scope of the loss.
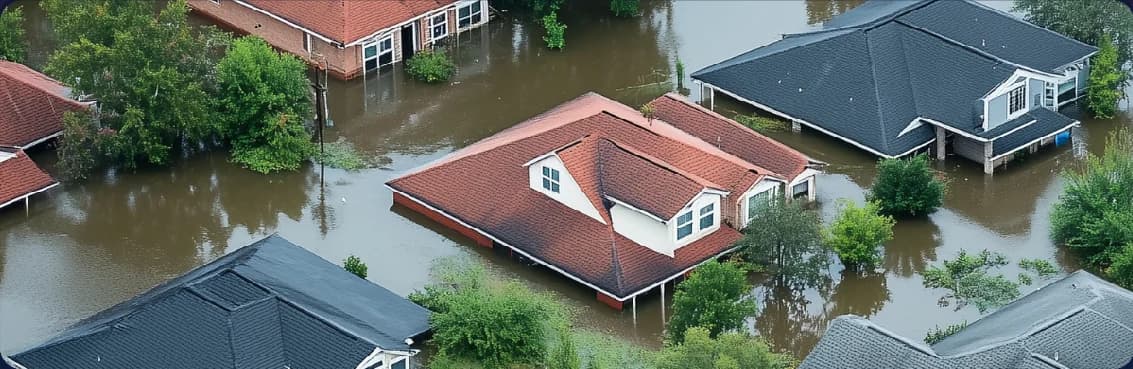
Flooding can compromise floors, walls, and foundations across an entire property or portfolio. We document every detail and pursue full compensation under every coverage that applies.
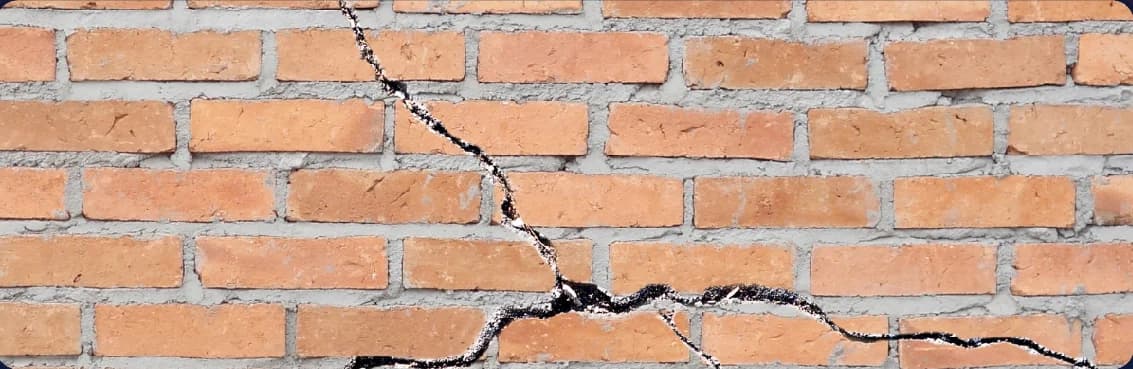
From roof assemblies to building envelopes, structural damage threatens the safety and value of the entire property. We bring in the right experts to document root cause and scope the full repair.
Lost rent, lost revenue, and extra operating expenses are real losses, and they're often underclaimed. We quantify the full financial impact so your business income coverage pays what it should.
The types of commercial losses we handle.
Healthcare and Hospitals
K-12 Schools and Universities
Multifamily Student Housing
Commercial and Retail Spaces
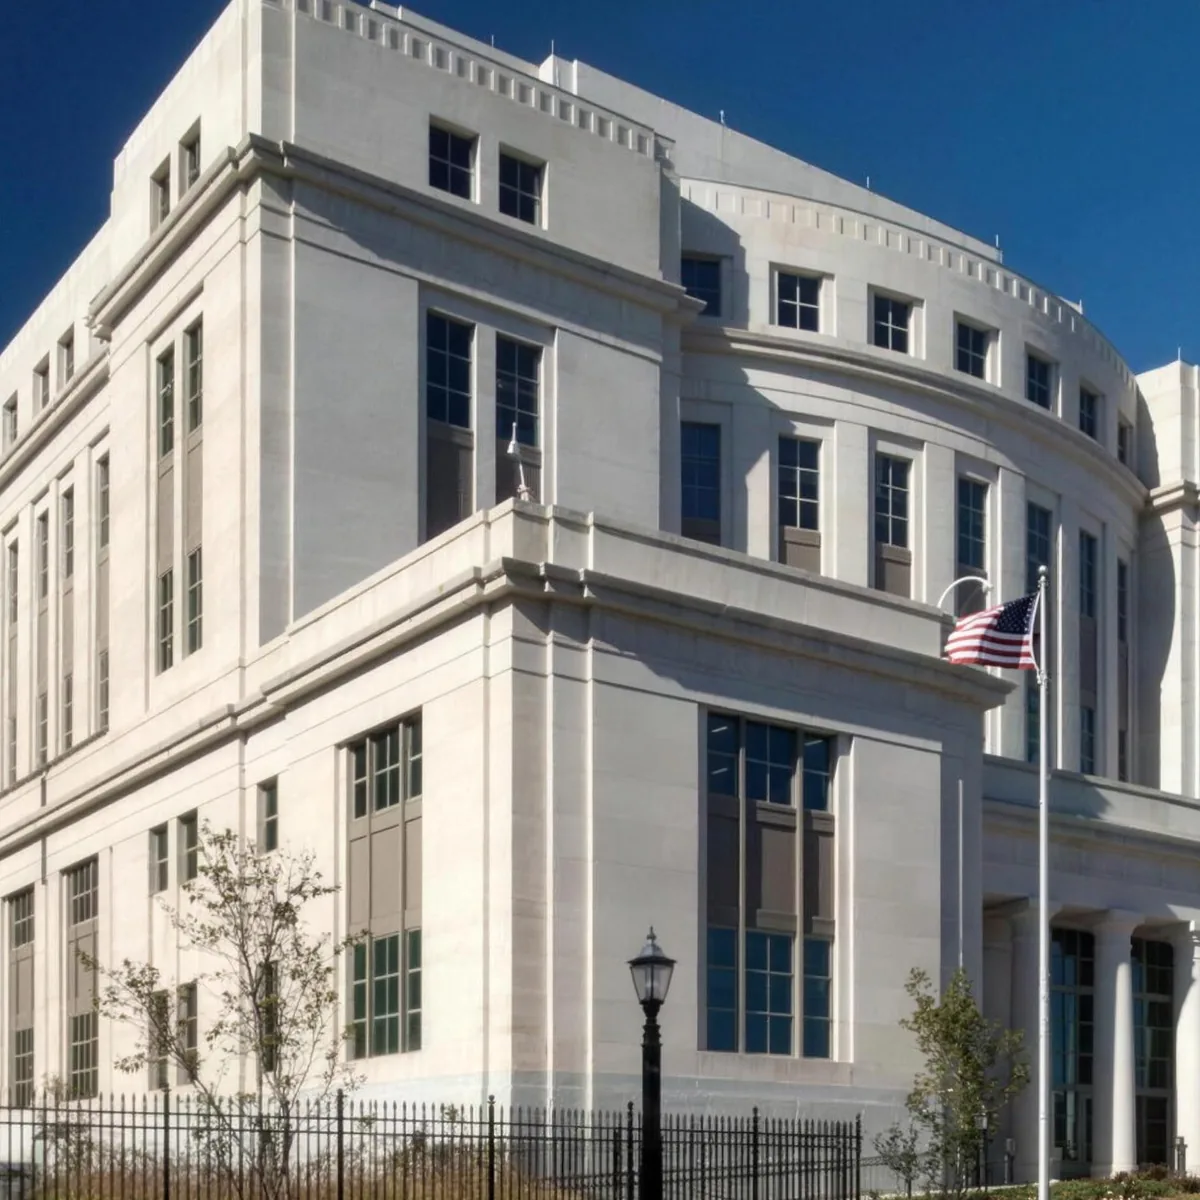
Government Buildings and Facilities
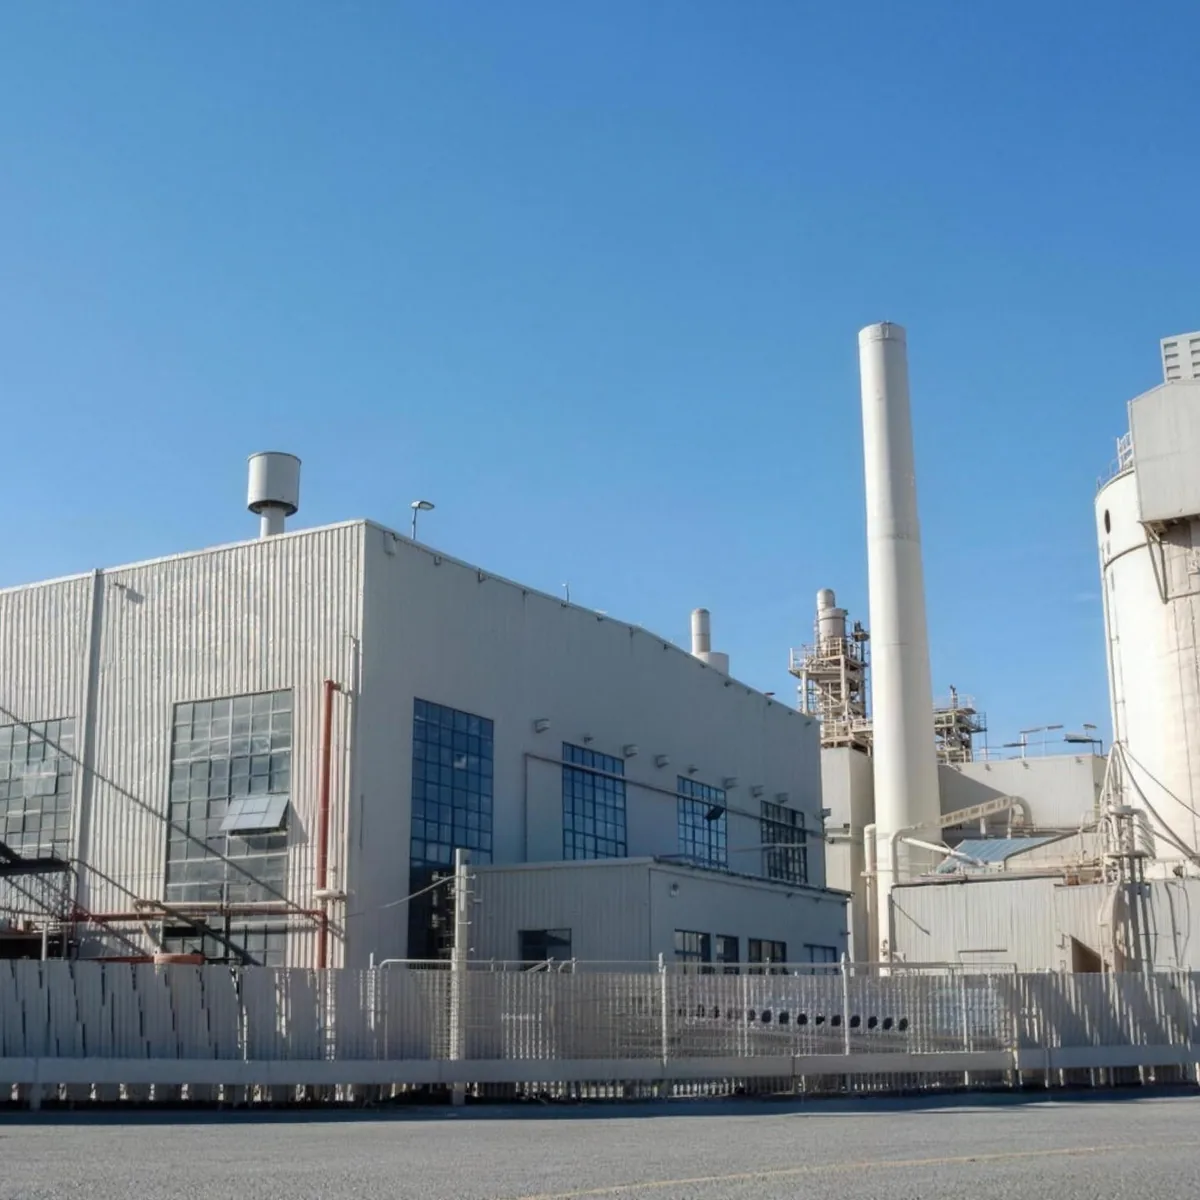
Industrial and Manufacturing Plants
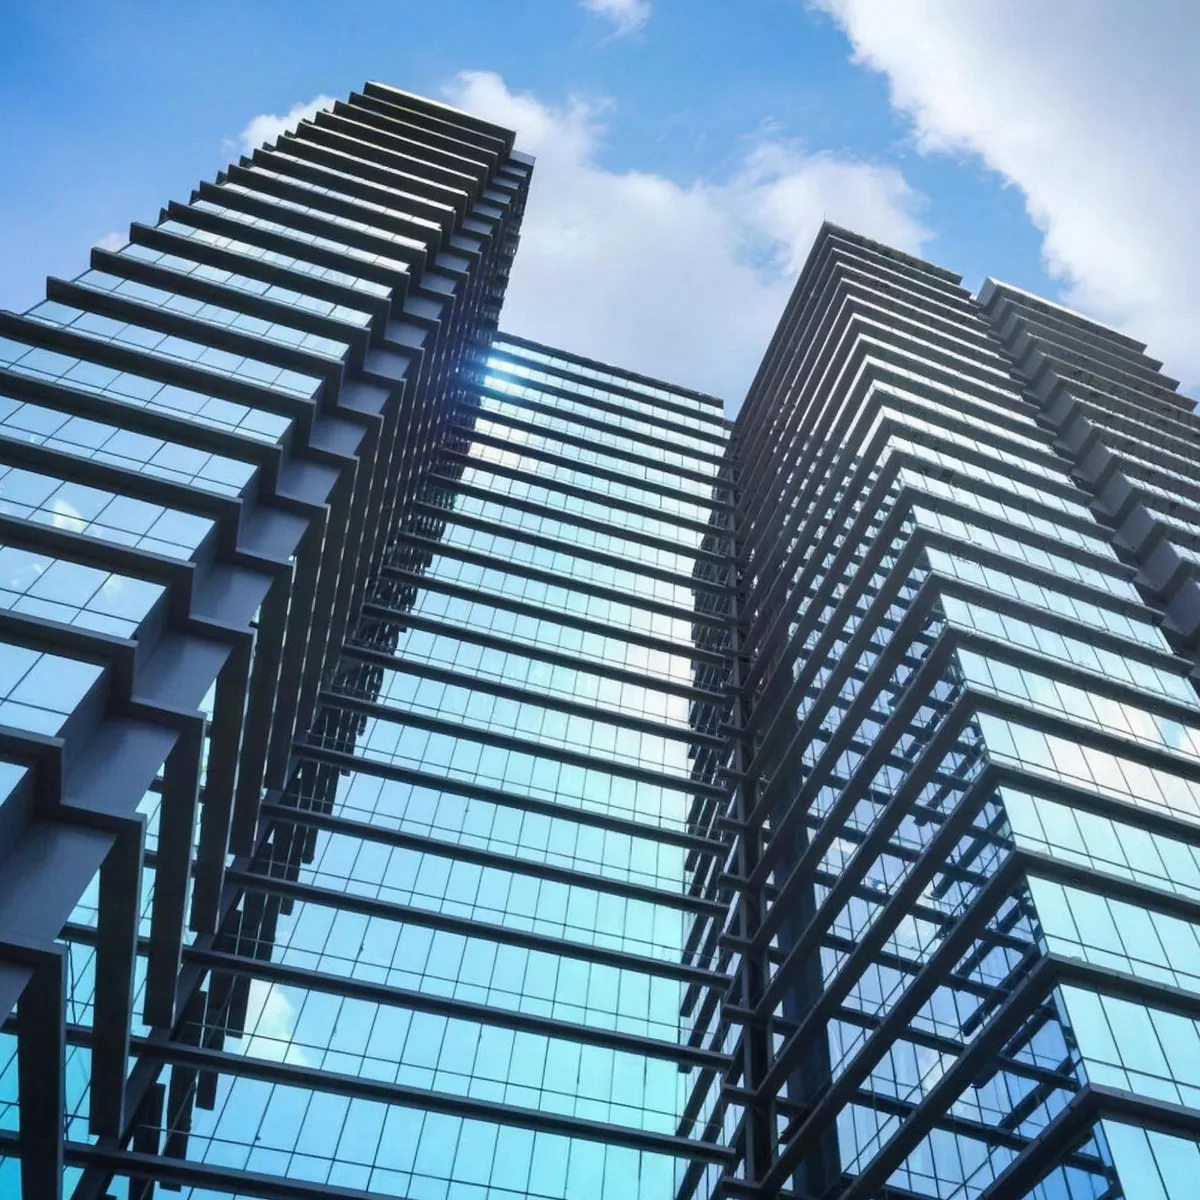
Commercial High-Rises
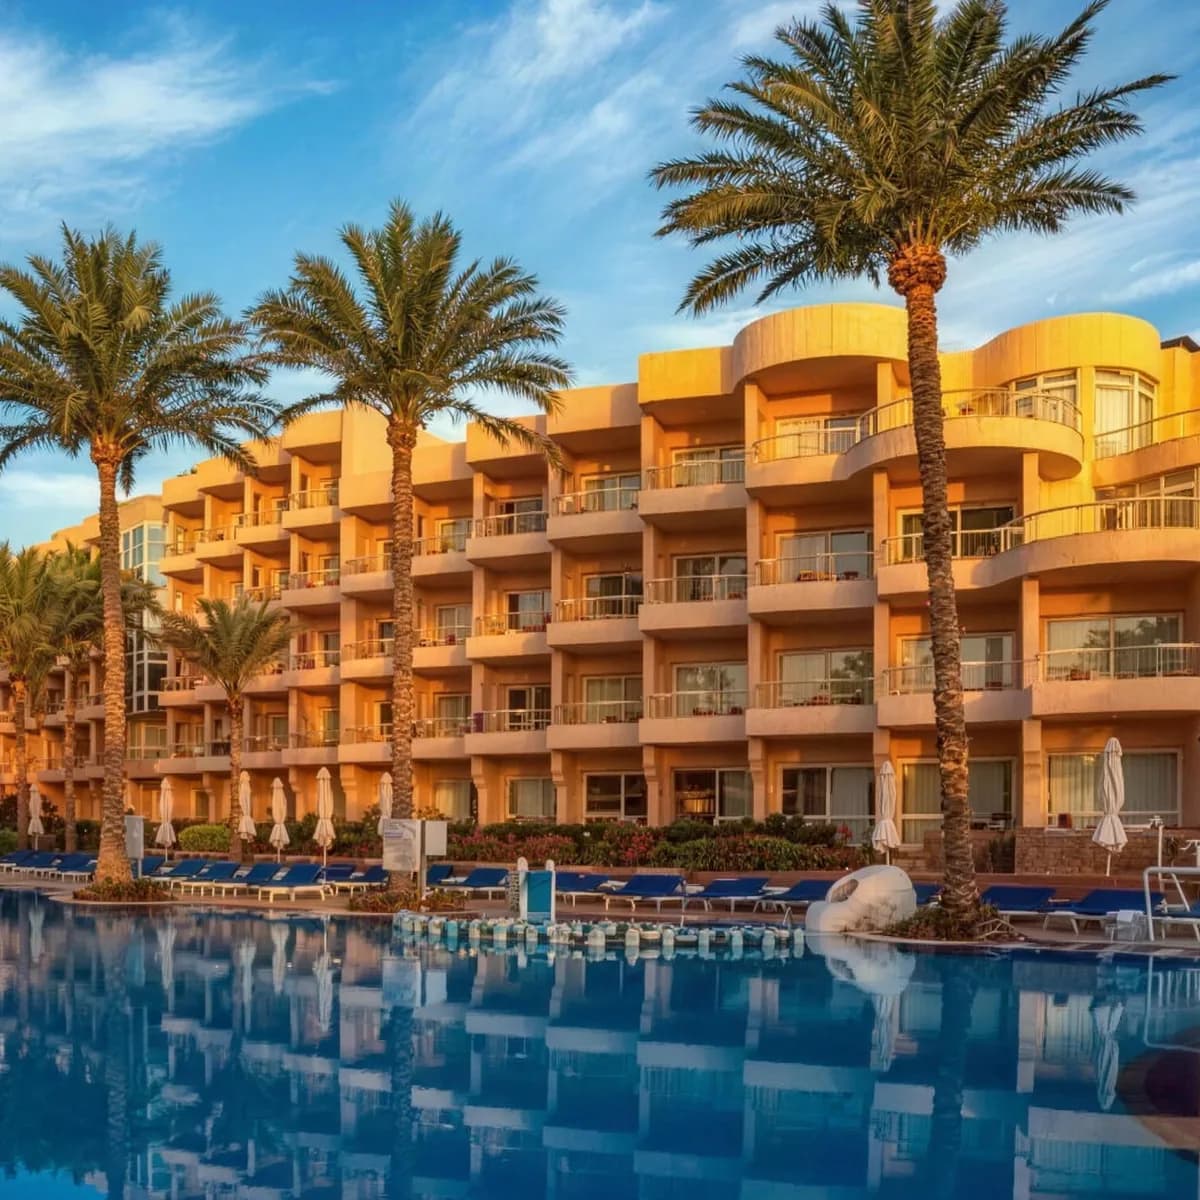
Hospitality: Hotels and Resorts
And how the Five Star process is built around it
Step 1
Complete a complimentary inspection of all roofs, exteriors, and interiors. Prepare a damage assessment checklist for scope.
Step 2
Navigate the policy's coverages, requirements, and deadlines to help avoid pitfalls and denials. Provide a recap of benefits and deductibles.
Step 3
Assess and gather the facts of the claim, explain our process, and engage directly with your association's decision-makers.
Step 4
File the claim with the insurance company and provide all necessary documentation to open it. Track down all desk adjusters, field adjusters, and contractors assigned by the carrier.
Step 5
Photograph, sketch, and obtain all required documentation to complete an Xactimate estimate of damage. Gather invoices and photos for prior repairs, engage engineering firms as needed, and review the package with the HOA before submitting it.
Step 6
Coordinate and attend all inspections with insurance company adjusters, contractors, and engineers.
Step 7
Lead negotiations and attend all re-inspections, mediations, and appraisals when a dispute arises.
Step 8
Review the carrier's estimates and all applicable bids with the insured, then discuss settlement and available options for pursuing appropriate payment.
How commercial policies became more restrictive, conditional and complex.
1990s
Direct physical loss generally covered unless excluded.
1992-2000
Hurricane Andrew reshapes underwriting. Percentage wind/hurricane deductibles expand.
2001-2009
Mold/fungi restrictions. Terrorism separated. Virus/bacteria exclusion introduced.
2012-2018
Roof ACV. Cosmetic hail limitations. Protective safeguard requirements.
2019-2022
Surplus-lines/manuscript forms. Arbitration provisions. Cyber exclusions.
2022-2026
Higher catastrophe deductibles. Roof schedules & ACV. Sublimits. Coinsurance exposure. Stricter conditions.
Then
Direct physical loss was generally covered unless excluded.
Now
A $10 million policy. But $10 million subject to what?
The policy limit is only the beginning of the coverage analysis.
More than ever, it pays to have an experienced public adjuster protecting your side of the claim.
Coverage varies by policy form, endorsement, carrier, jurisdiction and applicable law.
1,900+
Google Reviews
Verified client feedback from policyholders across Florida, on residential and commercial claims alike.
Commercial claim“Thank you for a job well done. We tried to handle the claim ourselves but without Five Star, we would not have been able to restore the value to our property.”
Commercial claim“After a free roof inspection, you agreed to represent the association on a contingency basis. In less than 60 days, your team of engineers, negotiators, and insurance experts got us an additional $550,000.00 cash!”
Google review“Five Star is called Five Star for a reason! Before my son introduced me to Five Star, I was getting nowhere with my insurance company. My Five Star Adjuster in shining armor handled it all.”
Google review“We hired Five Star after damage from Hurricane Milton. Our insurance company denied our initial claim. With Five Star's help, we recouped a settlement, and their diligence kept the process moving throughout.”
Google review“Five Star Claims Adjusting has been absolutely great and so pleasant to deal with: knowledgeable, responsive, and super nice. They took the stress away from us during this difficult time.”
Google review“Five Star Claims was super professional and detailed throughout every step of our claim process. They kept us abreast of what was happening at all times and worked extra hard for us! We recommend Five Star 100 percent!”
A true partnership.
The best outcomes happen when the right experts are focused on what they do best. Commercial claims involve far more moving parts than most property owners and managers realize, from contractors and engineers to accountants, attorneys, and insurance professionals. Five Star serves as one point of coordination, bringing those pieces together and keeping the claim moving in the right direction. If you're dealing with commercial property damage, our team is ready to step in and help.
Take Five Star With You
The commercial division, the track record, and the process, all in one shareable brochure. Share it with your board, your property manager, or your broker, so everyone involved in the decision sees the same picture.
Save Your Time | Handle Your Carrier | Maximize Your Claim
While insurance company adjusters are legally required to evaluate damages impartially, important details can sometimes be missed. Studies consistently show that claims managed by public adjusters typically result in significantly higher settlements. Since insurance companies aim to minimize their financial liability, it's not uncommon for payouts to be lower than what policyholders may be entitled to. Our services include detailed damage assessments, direct negotiation with insurance carriers, and coordination of settlements, all designed to protect and prioritize your best interests.
When disaster strikes, the insurance company sends their adjuster to protect their bottom line. We're here to protect yours. As licensed public adjusters, we work for you, not the insurer. From damage assessments and loss documentation to negotiations and final settlement, we take on the heavy lifting and push back when the insurance company tries to pay less than you deserve.
We don't get paid unless you do. It's that simple. We work on a contingency basis, which means there are no upfront fees and zero risk to you. Our fee is a small percentage of the final settlement, and only after we've recovered more money than the insurance company was willing to pay. If we don't increase your payout, you owe us nothing.
Absolutely! Denied and underpaid claims are one of our specialties. Insurance companies often try to minimize payouts, but we have the expertise to challenge their decision and get you the compensation you deserve.
Insurance companies have teams of adjusters working against you. Why not have an expert working for you? We know insurance policies inside out and find coverage you may not realize you have. We negotiate aggressively to increase your payout. And we handle all the paperwork and red tape, saving you time and stress.