Hurricane & Storm Surge
Wind and surge are separate perils under separate policies. We establish the sequence and the water line, because an unproven causation argument is a denied claim.
Property Damage in Sarasota?
Southwest Florida has taken the worst of two storms in three years — Ian in 2022 and Milton making landfall near Siesta Key in 2024. Both left the same argument behind: was it wind or was it surge? Policies treat those as different perils with different coverage, and the answer decides the claim. Five Star's licensed public adjusters work that question from our Sarasota office.
Call Our Sarasota Team: (941) 202-2343
Insurance companies have a team working to minimize what they pay you. You deserve the same expertise on your side.
Five Star’s public adjusters step in immediately after a loss to manage every aspect of your claim — from documentation to negotiation — so nothing gets left on the table.
On this coast the fight is usually causation, not damage. Everyone agrees the property is wrecked; the dispute is which peril did it, because that is what decides who pays.
Wind and surge are separate perils under separate policies. We establish the sequence and the water line, because an unproven causation argument is a denied claim.
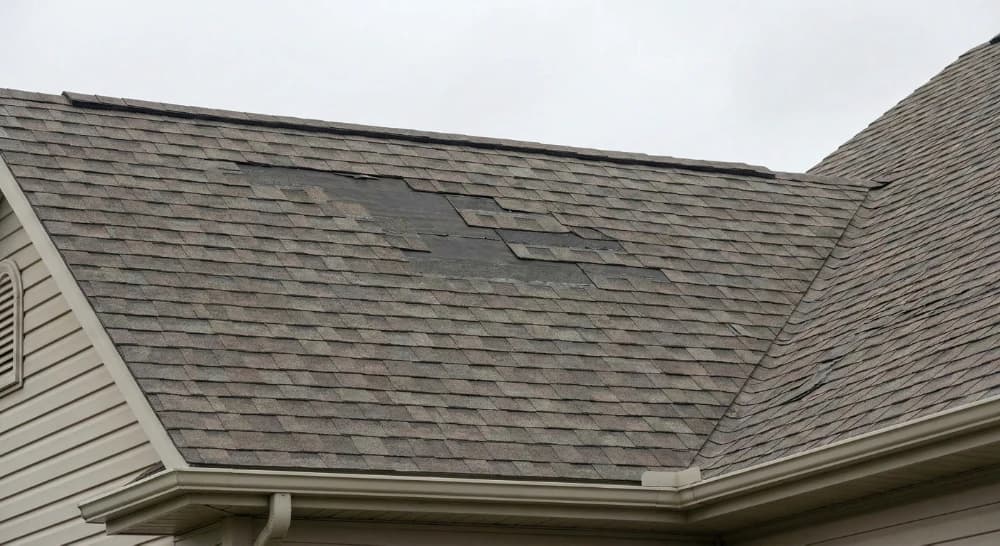
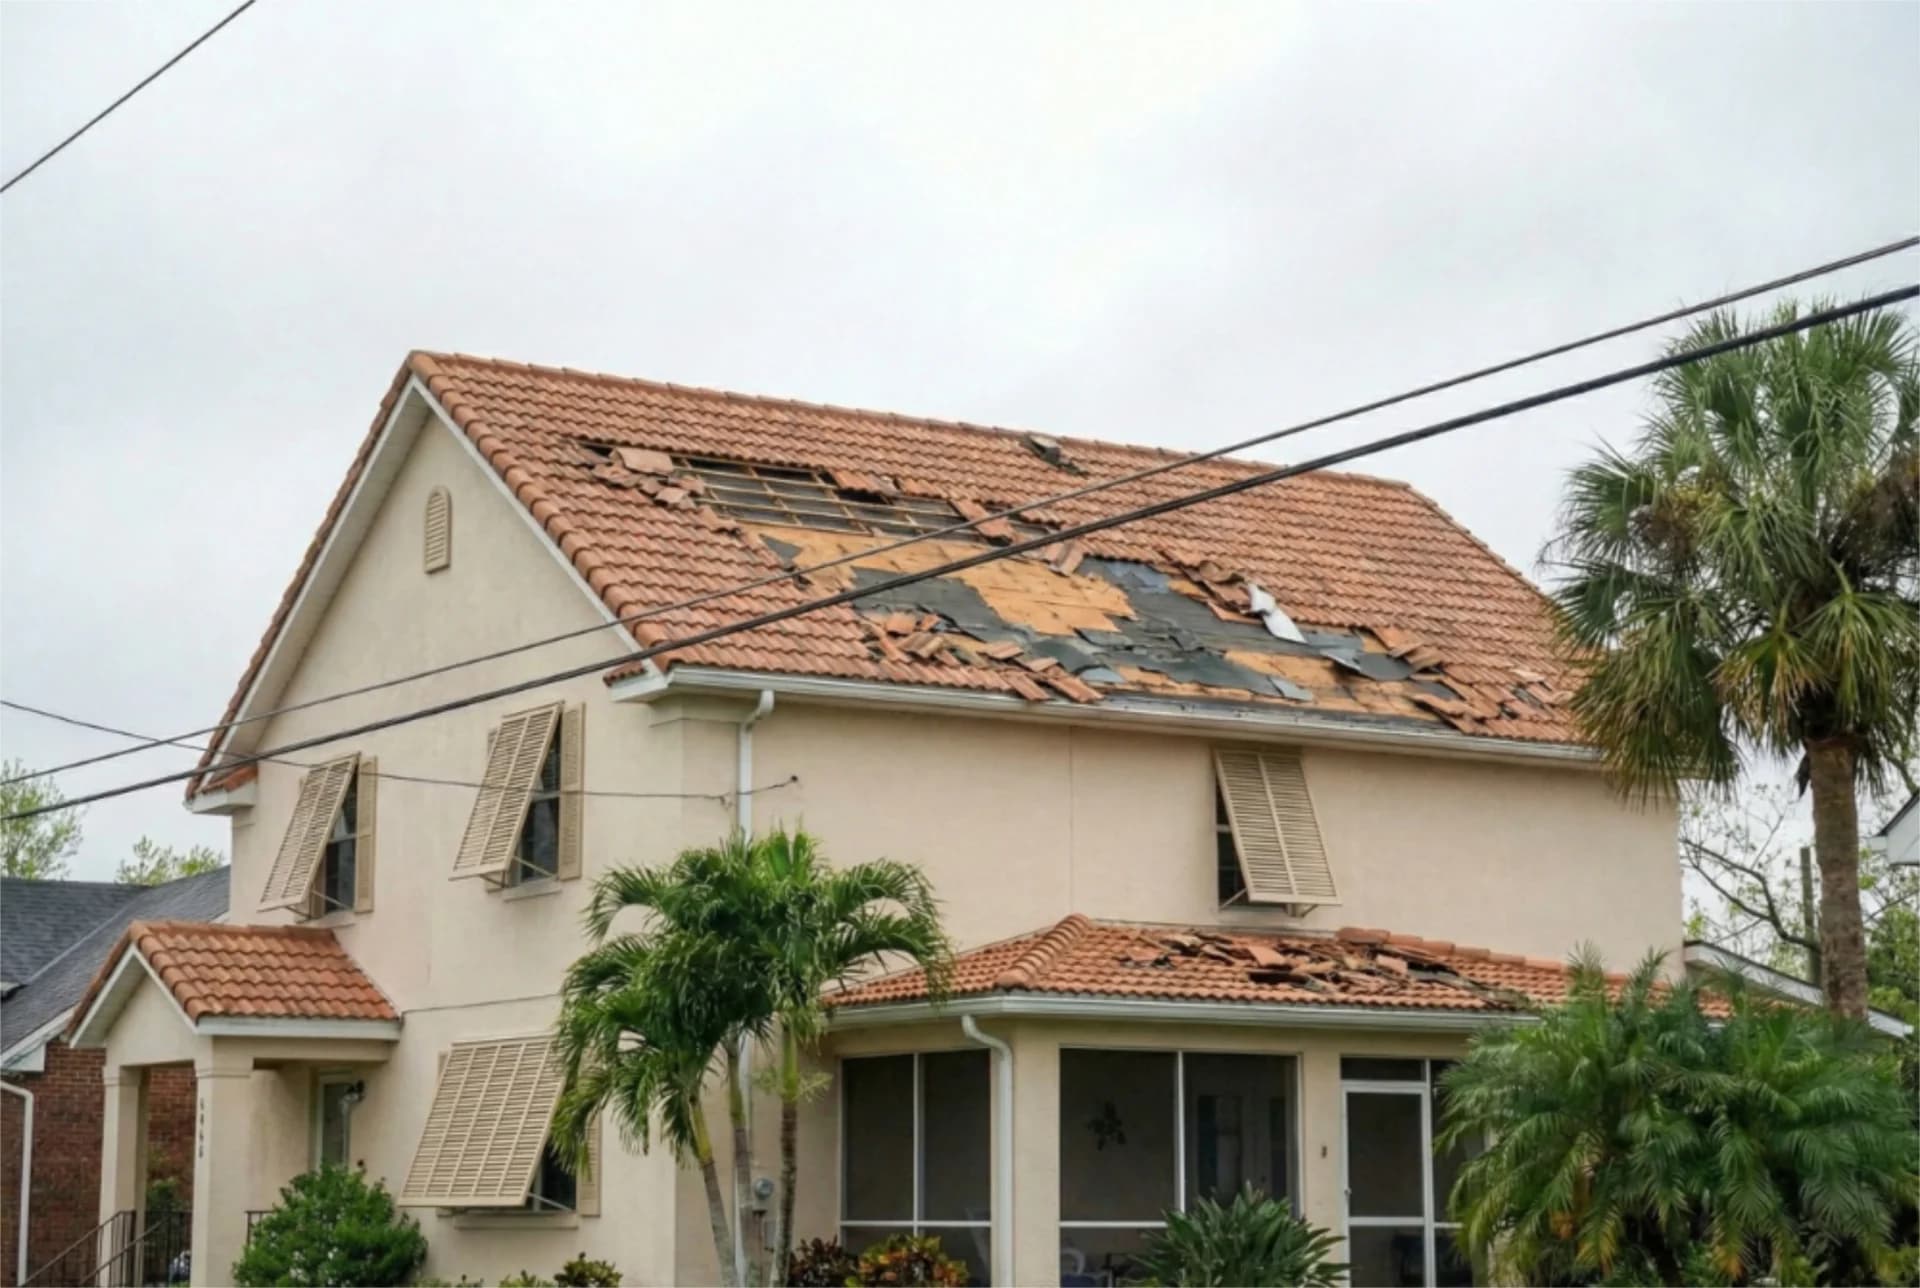
Tile and shingle uplift that reads as cosmetic to a desk adjuster, and the interior damage underneath it that gets separated out and underpaid.
Sarasota County has been hit by three hurricanes in three years. Ian came ashore at Cayo Costa in September 2022, and parts of North Port flooded as the Myakka River kept rising for days afterward. In 2024, Helene passed offshore in late September and pushed storm surge onto Siesta Key, Lido Key and Longboat Key, and two weeks later Milton made landfall near Siesta Key itself. Many homes here have been damaged more than once, and that is exactly what makes claims in this area harder to settle.
A homeowners policy covers wind; it excludes flood, which needs a separate flood policy (and new flood policies usually have a 30-day waiting period). When surge and wind hit the same building, the insurer will often attribute as much of the damage as it can to the peril it doesn't cover. When a home was hit by Helene's surge and then Milton's wind two weeks apart, separating the two is a matter of evidence: water lines, debris patterns, roof and window damage, and photographs taken between the storms. We build that record so the wind portion of your claim is paid in full.
Florida hurricane deductibles are usually a percentage of the dwelling limit, commonly 2%, 5% or 10%, and Florida law generally treats the hurricane deductible as an amount for the calendar year rather than for each storm. If you paid toward it on one 2024 hurricane, it should not have been charged again in full on the next. If claims from two hurricanes in the same year each carried a full deductible, ask your insurer to show its calculation.
In a condominium, the association's master policy and your own unit-owner (HO-6) policy each cover different parts of the same damage, and the line between them is set by your declaration of condominium and Florida law. Claims stall when the association and the unit owner each point at the other. We read both policies against the declaration and pursue each insurer for its share.
Under the Florida Building Code, replacing more than 25% of a roof within a 12-month period generally means the whole roof has to be brought up to current code, unless the existing roof was already built to the 2007 code or later. After repeated storms, many Sarasota roofs cross that line, and an estimate that patches a few squares when the code requires a full replacement is an underpaid claim.
Yes. Our Southwest Florida office is at 6151 Lake Osprey Drive, Suite 345, Sarasota, FL 34240, and you can reach the Sarasota team at (941) 202-2343. We come to the property to inspect the damage.
Florida now requires notice of a new or reopened property claim within one year of the date of loss, and a supplemental claim within 18 months, so most new claims from the 2024 storms are past those deadlines. If you already have an open claim, a dispute or an appraisal in progress, a free review can tell you what options remain.
Ask for the denial or the partial payment explanation in writing, along with any engineering report it relied on. Causation is often decided by evidence the insurer didn't collect: roof and opening damage, interior water lines and photographs taken between storms. We document wind damage separately so that what the homeowners policy covers is paid, whether or not you also have flood insurance.
There is no upfront cost. We are paid a percentage of what the insurer pays on the claim, and only if we recover money for you. Florida law caps public adjuster fees at 20% of the claim payment, and at 10% for claims from a declared state of emergency during the first year after the event.
Real Results
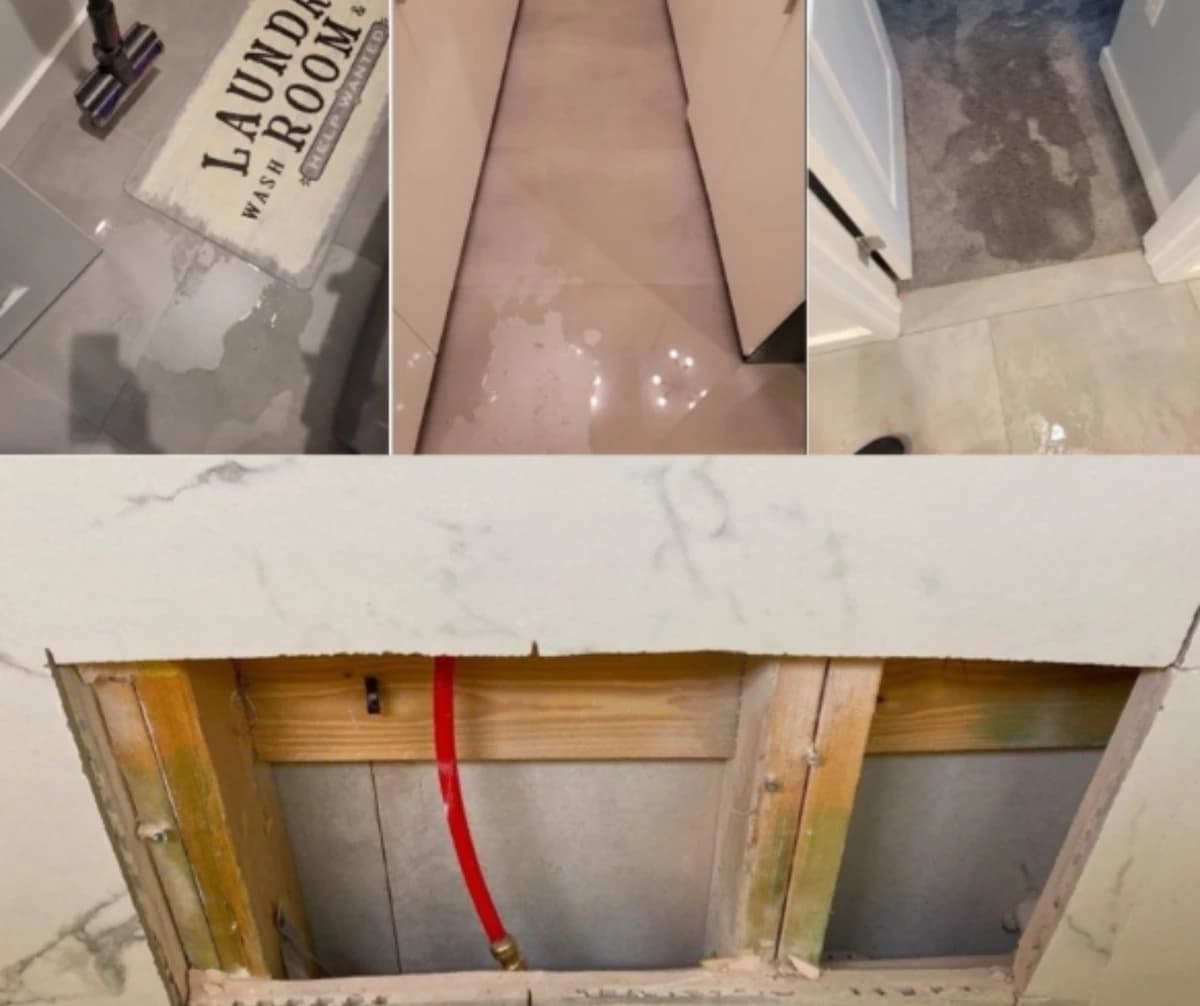
Initial Insurance Offers $9,211
Five Star Result: $82,425
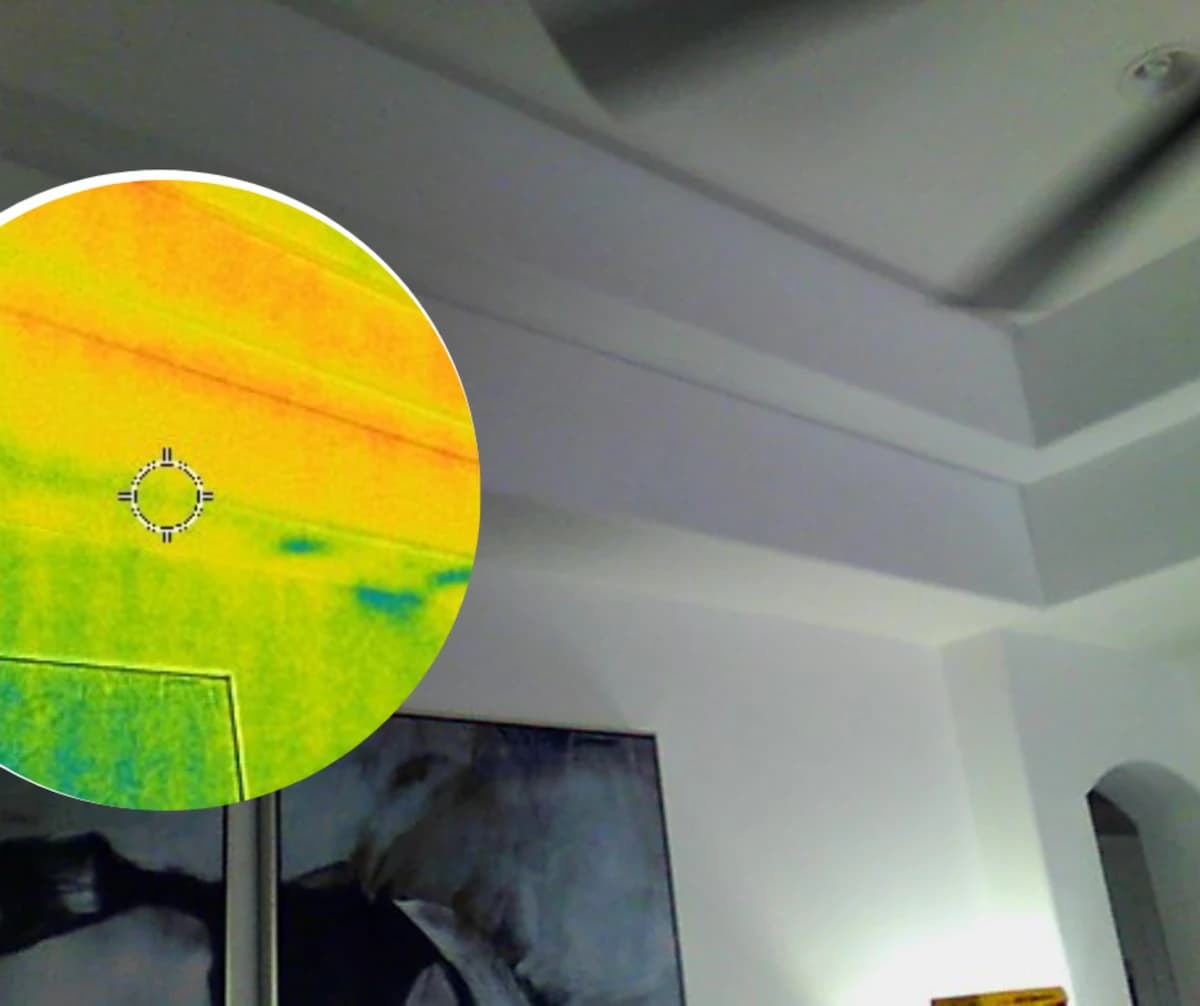
Initial Insurance Offers $20,646
Five Star Result: $147,000
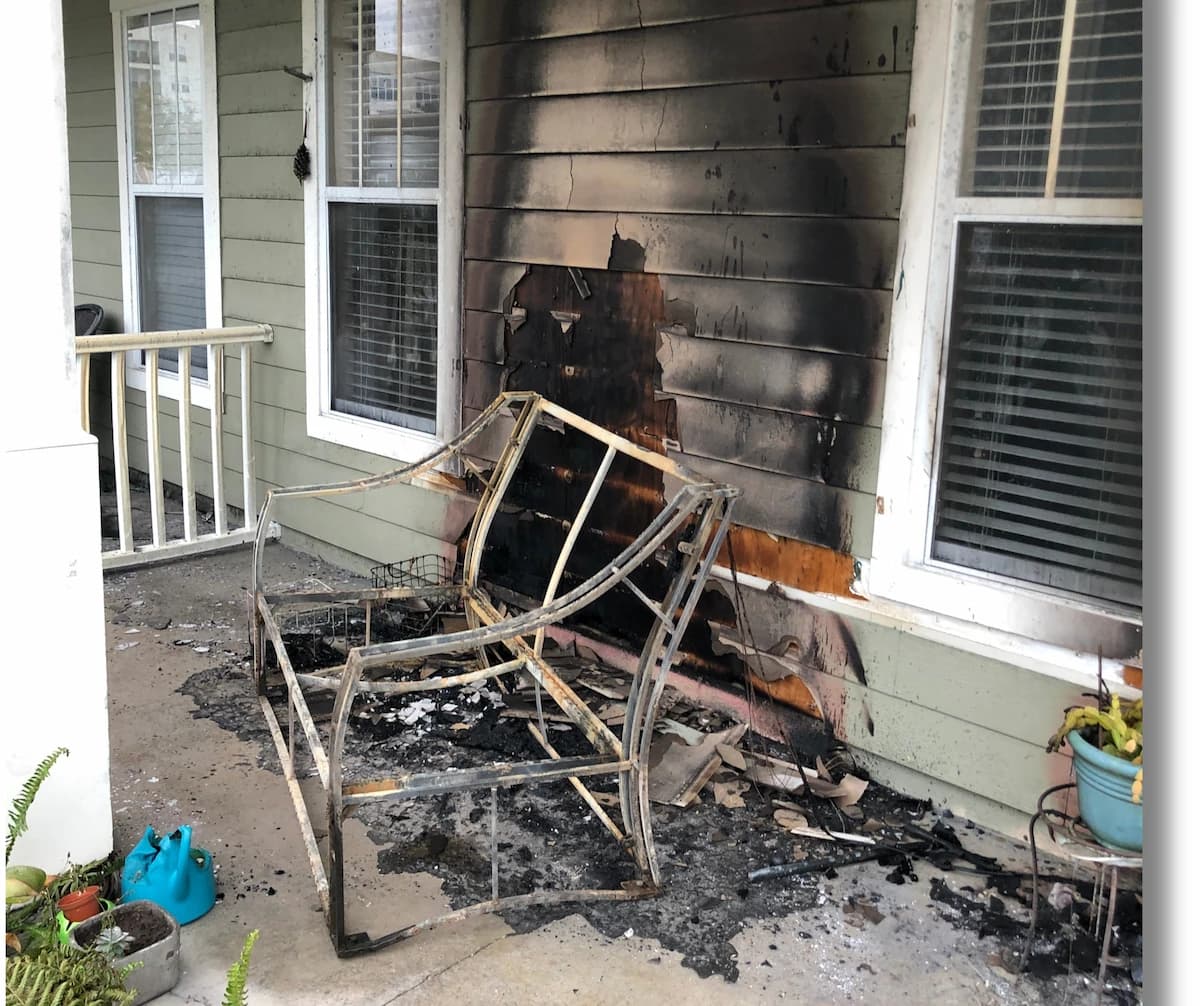
Initial Insurance Offers $19,118
Five Star Result: $37,088
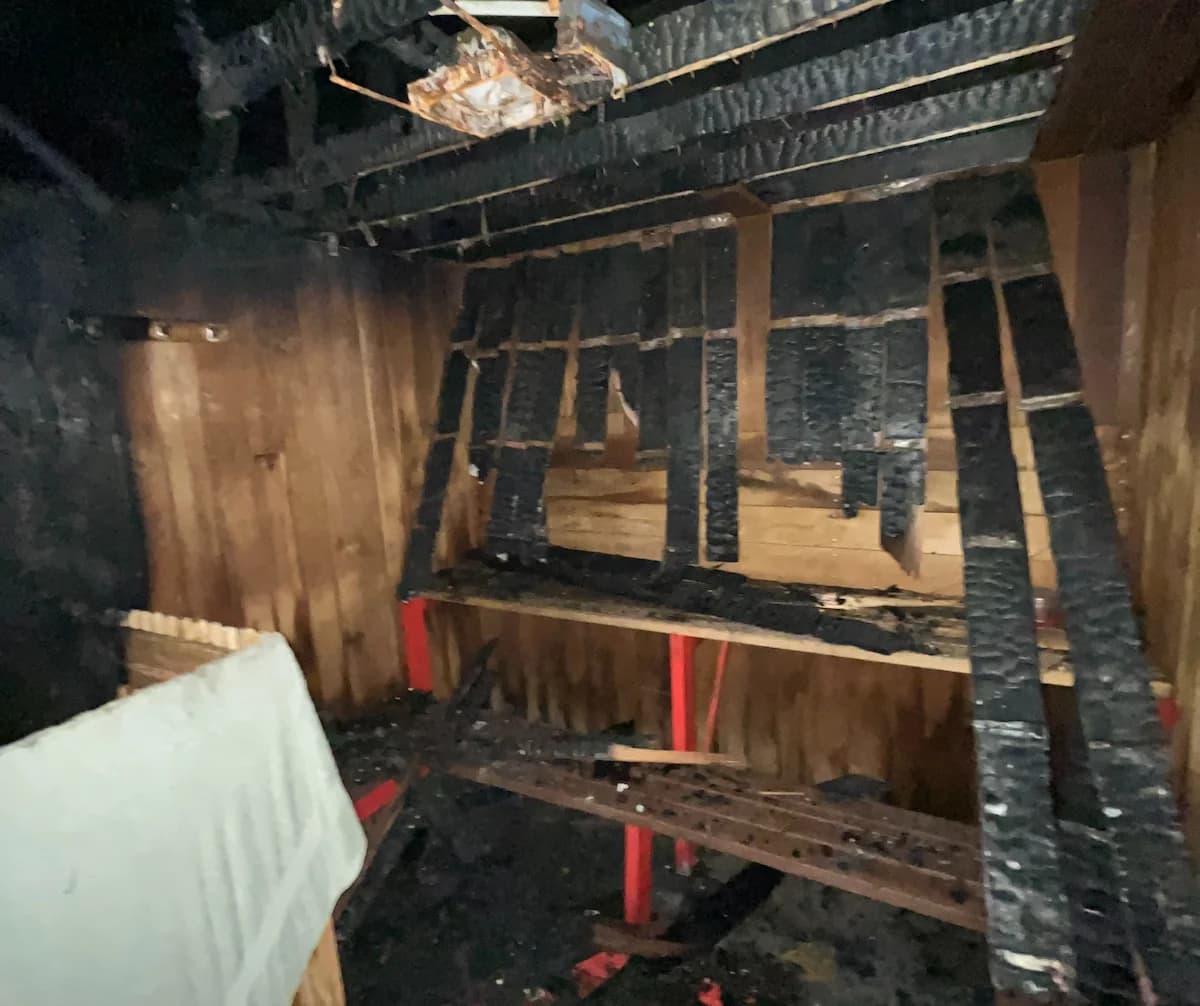
Initial Insurance Offers $740,182
Five Star Result: $2,112,227
Backed by Google Reviews Across Florida
Five Star Claims was super professional and detailed throughout every step of our claim process. They kept us abreast of what was happening at all times and worked extra hard for us! We recommend Five Star 100 percent!
Five Star made a difficult process seamless, painless, and easy. I strongly recommend their services when dealing with difficult insurance claims, and you will be a satisfied client like me.
I had a great experience with Five Star Claims. They are very professional and great communication through the process. A+ company
Thank you for all your help. You made this experience easier. Your commitment to do right by us is admirable. You made sure we understood the process and made sure communication was clear and consistent.
Five Star is truly phenomenal. They handled my claim as if I were a family member. They were courteous, caring, attentive, and communicated through the entire process.
Five Star did a wonderful job handling my claim. I would highly recommend them!
Trustworthy and effective! Five Star Claims Adjusting goes above and beyond.
I had a great experience! Help me with all the questions that I had and solve every problem easily!
The professionalism and honesty were outstanding. Most definitely recommend 5 Star if you are searching.