Flood & Water Damage
Rainfall flooding and drainage backup rarely arrive alone. We establish the source, because the source is what decides which policy responds.
Property Damage in Fort Lauderdale?
Five Star Fort Lauderdale, LLC works Broward claims from our office on W Oakland Park Blvd, about five miles from downtown. The April 2023 flood put roughly two feet of rain on this city in a day and produced years of disputed claims; between that, coastal wind and a condo market under fresh structural scrutiny, Fort Lauderdale property owners rarely get offered what their policy owes without someone arguing for it.
Call Our Fort Lauderdale Team: (954) 302-1106
Insurance companies have a team working to minimize what they pay you. You deserve the same expertise on your side.
Five Star’s public adjusters step in immediately after a loss to manage every aspect of your claim — from documentation to negotiation — so nothing gets left on the table.
Coastal Broward claims stack perils — wind, rain, surge and drainage in one loss. Insurers pay each differently, which is exactly why they get separated out and underpaid.
Rainfall flooding and drainage backup rarely arrive alone. We establish the source, because the source is what decides which policy responds.
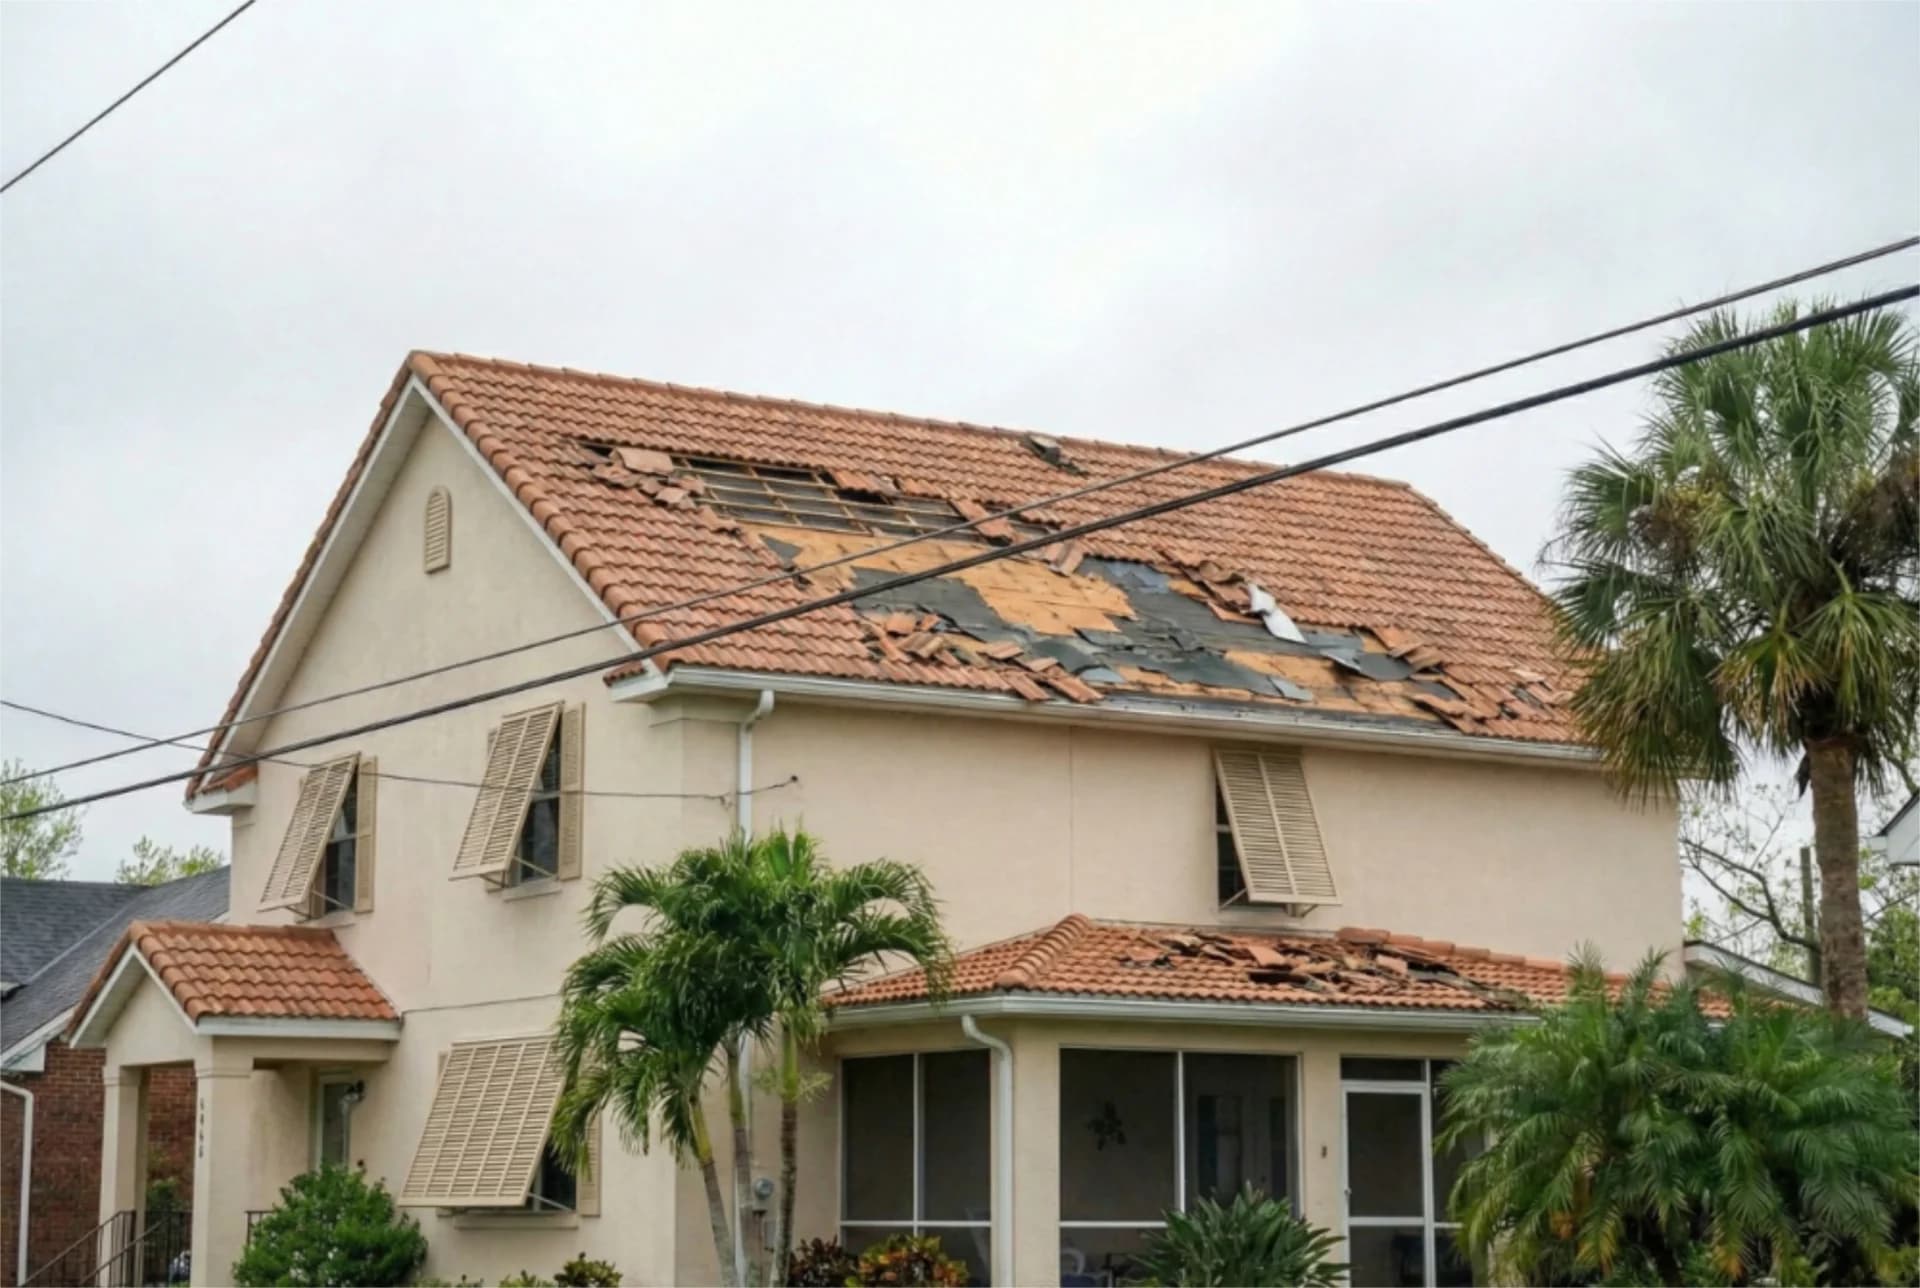
Coastal wind damage, opened envelopes and the water that comes in behind them — documented as one loss rather than several convenient ones.
Five Star Fort Lauderdale, LLC handles claims across the city from our office on W Oakland Park Blvd, about five miles north of downtown. Fort Lauderdale claims have their own character: a city laced with canals and close to sea level, a skyline of condominium towers, and a large base of commercial property. These are the issues that come up most.
On April 12, 2023, more than 25 inches of rain fell at Fort Lauderdale's airport in roughly a day, the most in the city's recorded history. Much of the damage came from water that rose from outside, which is flood, and from water that backed up through floor drains, toilets and sewer lines. A standard homeowners policy excludes both. Flood is covered only by a flood policy, and backup is covered only if you added a water backup endorsement, which usually carries its own limit. If you have either, the claim turns on proving which way the water came in.
After the Surfside collapse, Florida law began requiring milestone structural inspections and reserve studies for condominium buildings three stories and taller, and many Fort Lauderdale associations are now funding repairs and raising assessments. When storm or water damage happens, the association's master policy and each owner's HO-6 policy cover different parts of the building, set by the declaration of condominium. Owners are also often surprised by how small the loss assessment coverage on their HO-6 is when the association passes a deductible or uninsured loss on to them. We read the master policy, the unit policy and the declaration together.
Offices, retail, restaurants, marinas and multifamily buildings bring commercial policies with business income coverage, coinsurance clauses and percentage deductibles. A claim that reaches business income or an interrupted operation needs the loss documented from the first day. See our commercial claims page for how we handle them.
Hurricane wind damage to windows, roofs and building envelopes on the barrier island and the waterfront often lets rain in behind it. Under the standard opening rule, rain damage is covered when the wind first created the opening, so documenting the opening is what gets the interior damage paid.
Our South Florida office, operating as Five Star Fort Lauderdale, LLC, is at 1640 W Oakland Park Blvd #202, Oakland Park, FL 33311, about five miles from downtown Fort Lauderdale. Call (954) 302-1106. We inspect at your property.
Not under a standard policy. Water backup through drains and sewers is excluded unless you bought a water backup endorsement, and rising water from outside is flood, which needs a flood policy. Check your declarations page for a backup endorsement and its limit.
It depends on your declaration of condominium and Florida law, which divide the building between the association's master policy and your HO-6 policy. Typically the association insures the structure and common elements, and you insure your interior finishes and contents, but the details vary by building. We review both policies and the declaration to find every party that owes on the claim.
Yes, including retail, office, restaurant, marine and multifamily property, along with business income losses. Our commercial claims page has more on how we work them.
Real Results
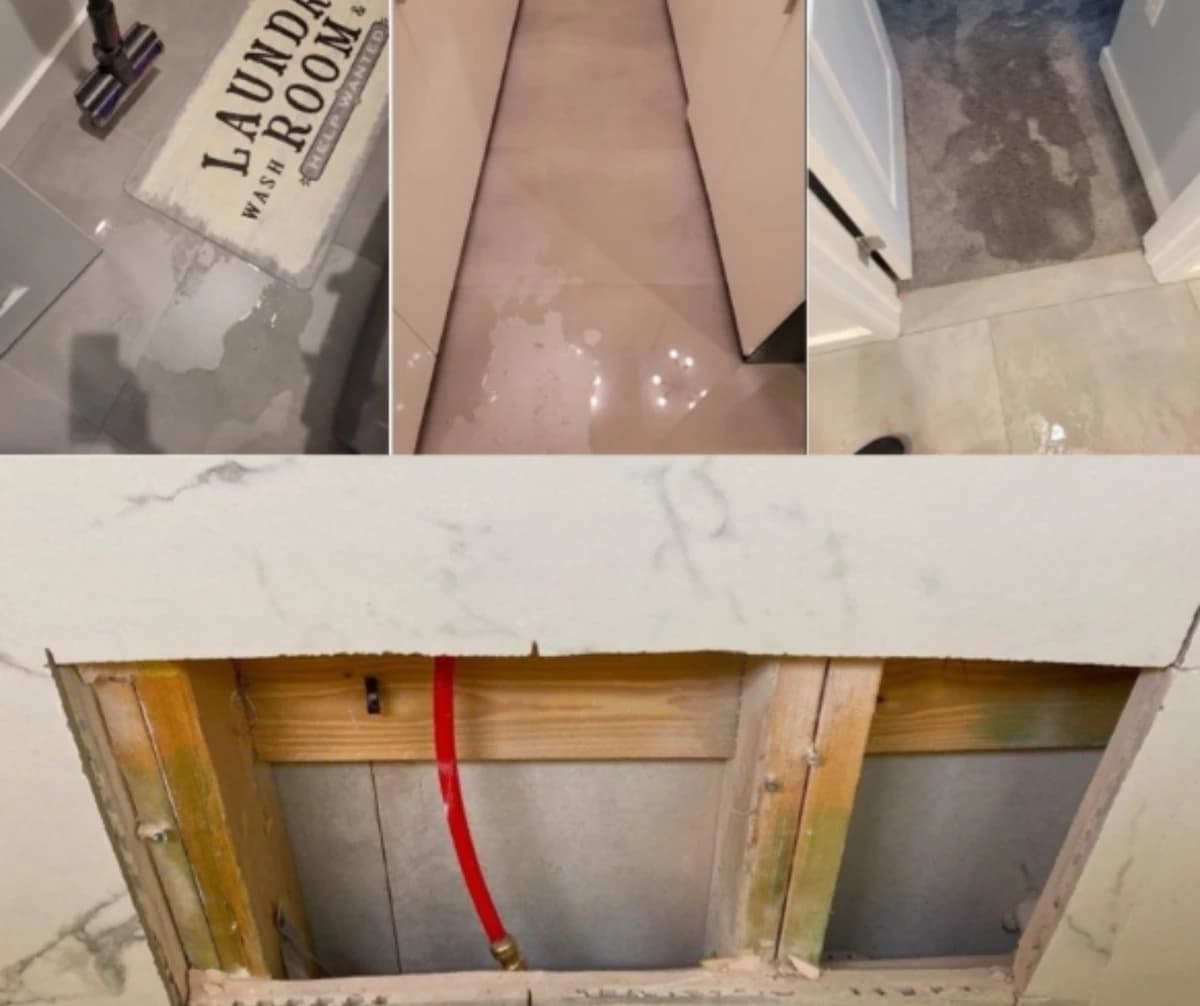
Initial Insurance Offers $9,211
Five Star Result: $82,425
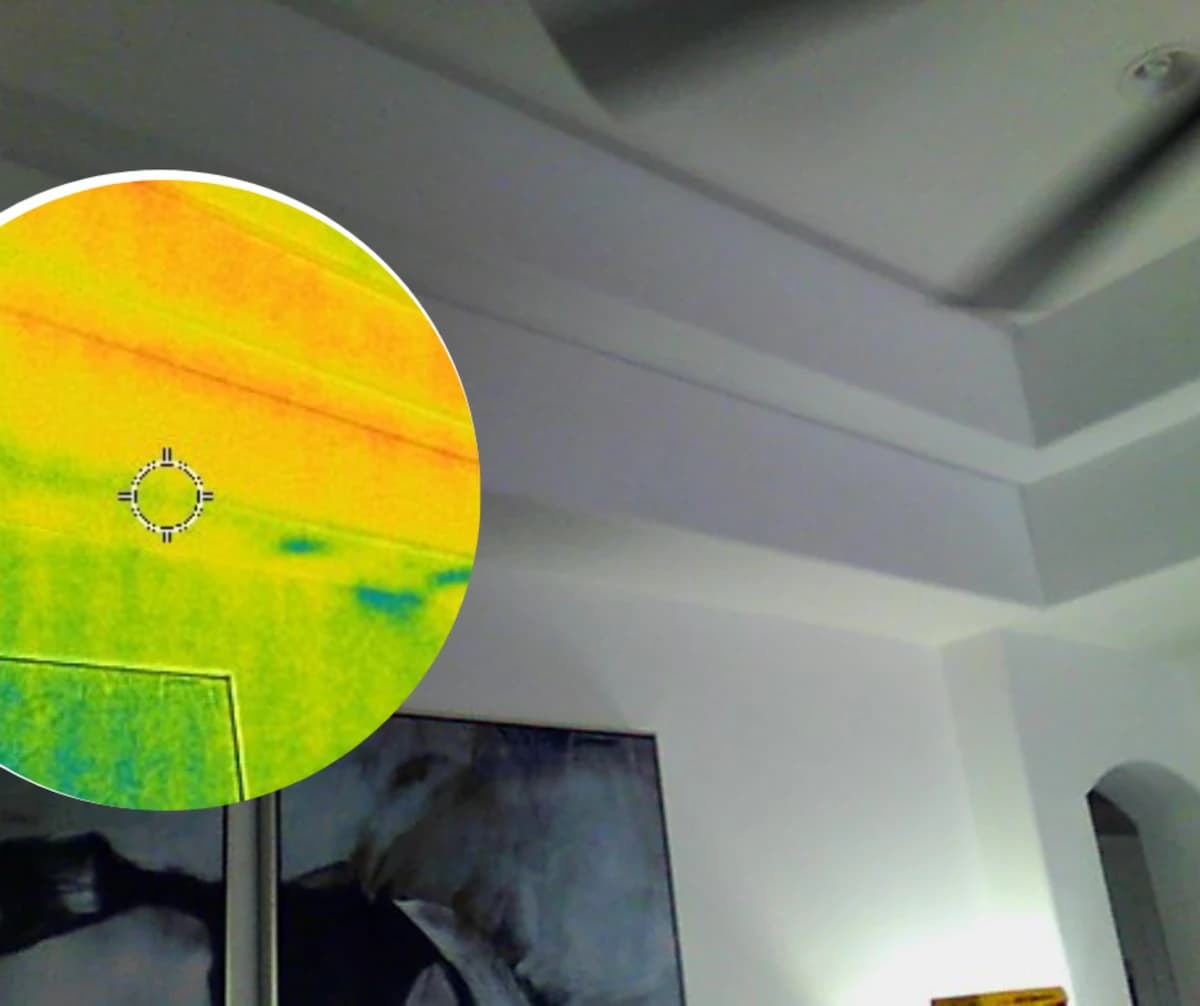
Initial Insurance Offers $20,646
Five Star Result: $147,000
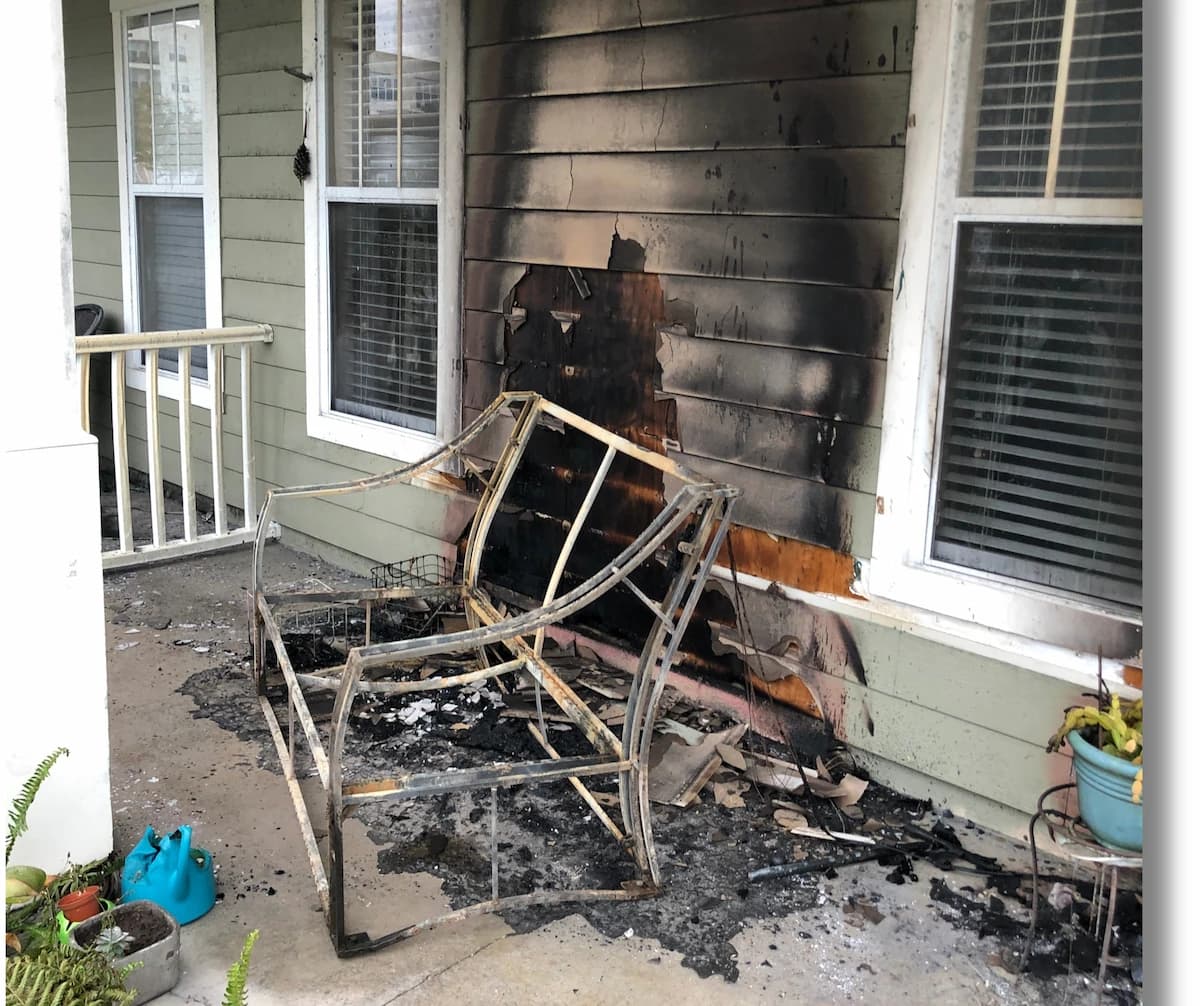
Initial Insurance Offers $19,118
Five Star Result: $37,088
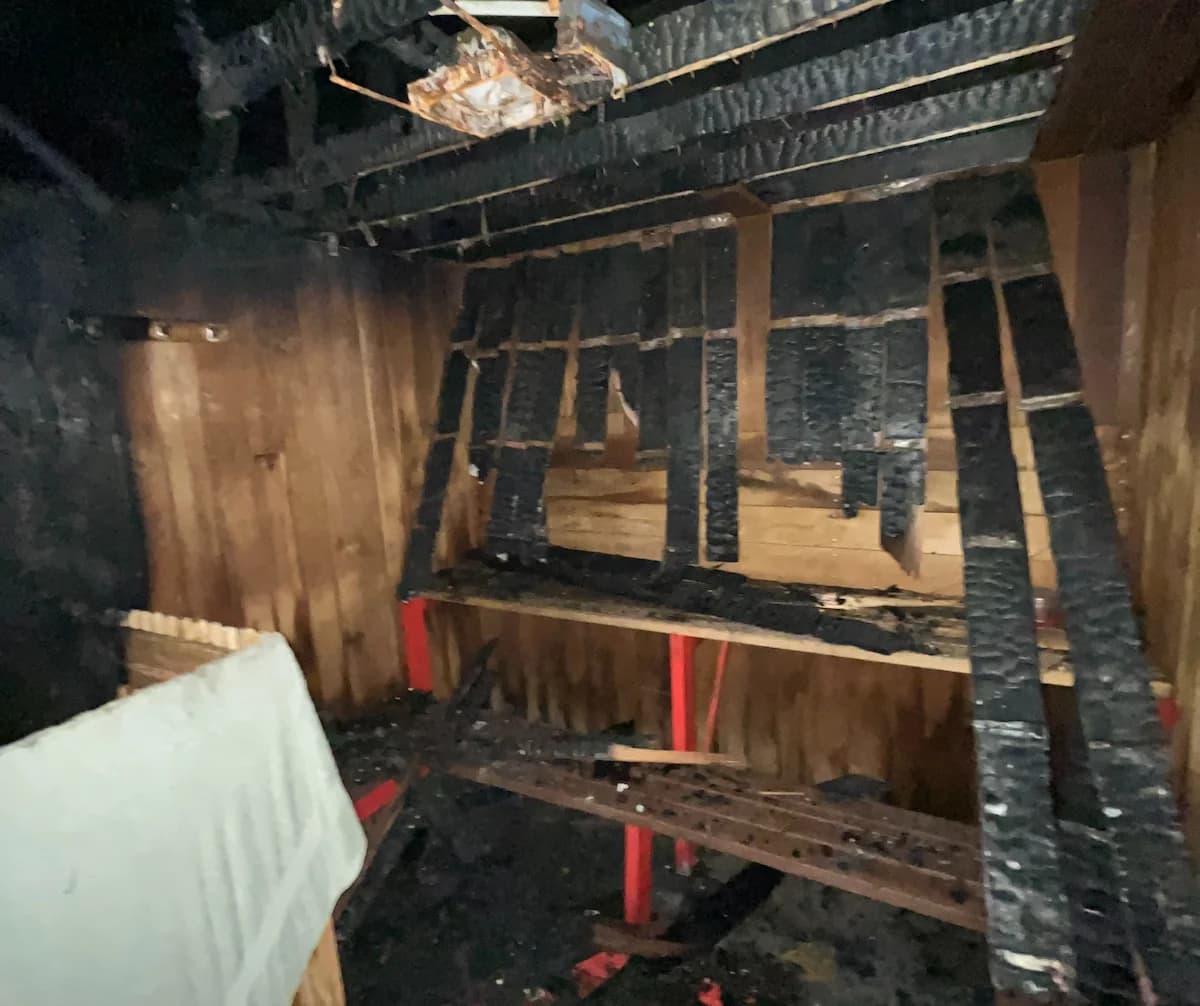
Initial Insurance Offers $740,182
Five Star Result: $2,112,227
Backed by Google Reviews Across Florida
Five Star Claims was super professional and detailed throughout every step of our claim process. They kept us abreast of what was happening at all times and worked extra hard for us! We recommend Five Star 100 percent!
Five Star made a difficult process seamless, painless, and easy. I strongly recommend their services when dealing with difficult insurance claims, and you will be a satisfied client like me.
I had a great experience with Five Star Claims. They are very professional and great communication through the process. A+ company
Thank you for all your help. You made this experience easier. Your commitment to do right by us is admirable. You made sure we understood the process and made sure communication was clear and consistent.
Five Star is truly phenomenal. They handled my claim as if I were a family member. They were courteous, caring, attentive, and communicated through the entire process.
Five Star did a wonderful job handling my claim. I would highly recommend them!
Trustworthy and effective! Five Star Claims Adjusting goes above and beyond.
I had a great experience! Help me with all the questions that I had and solve every problem easily!
The professionalism and honesty were outstanding. Most definitely recommend 5 Star if you are searching.