Hail & Wind Damage
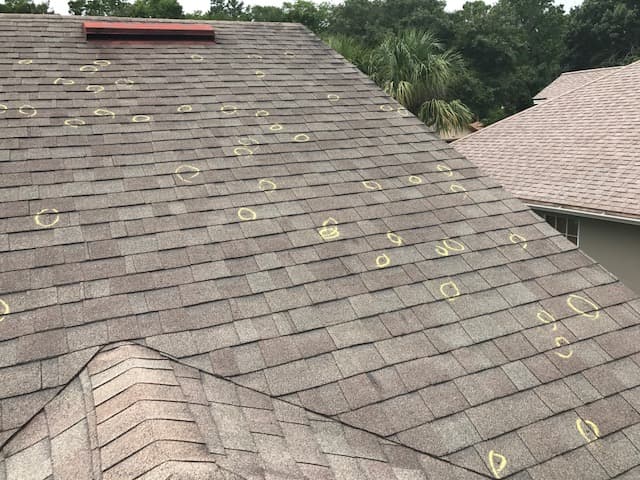
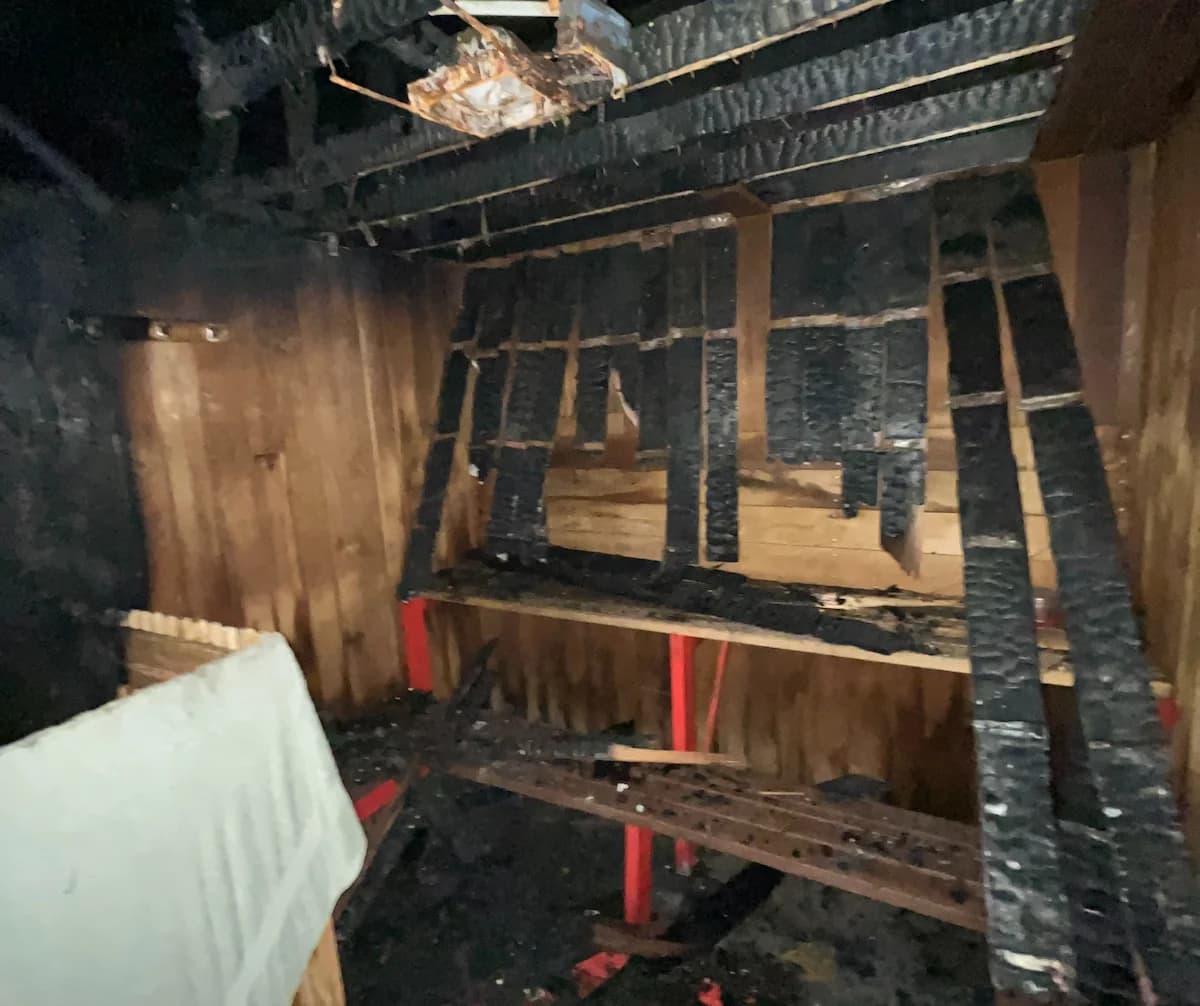
Spring hail and straight line wind open the building envelope. What follows is usually called water damage and paid at a fraction of what the wind claim would have been worth.
Property Damage in Houston?
Five Star's Texas line is a Houston number and our licensed adjusters work Gulf Coast claims from the Dallas office. Houston stacks perils in a way North Texas does not: hail and straight line wind in spring, tropical systems and the rainfall that comes with them later in the year. Policies treat wind, hail and flood as separate perils with separate coverage, so which one caused your loss decides whether it is paid at all.
Call Our Houston Team: (713) 487-5167
Insurance companies have a team working to minimize what they pay you. You deserve the same expertise on your side.
Five Star's public adjusters establish which peril caused what, in the order it happened, because on the Gulf Coast that single question decides which policy responds. Serving Houston and homeowners across Texas.
On the Gulf Coast one storm produces several perils, and a claim gets split along those lines. Where the water came from is worth more than what it damaged.
Spring hail and straight line wind open the building envelope. What follows is usually called water damage and paid at a fraction of what the wind claim would have been worth.
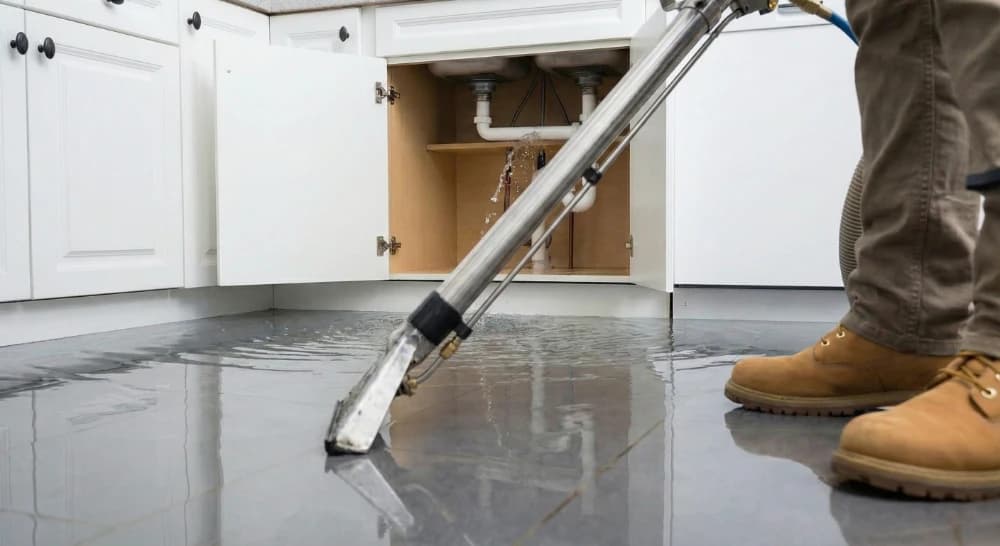
Wind driven rain through a damaged roof and rising water at the door are different perils under different policies. We prove the path the water took, because that is what decides who pays.
Five Star's Texas phone line is a Houston number, and our licensed adjusters work Houston and Gulf Coast claims from our Texas office in Dallas. No other part of the state stacks perils the way Houston does: tropical systems, flooding rain and severe wind, sometimes within weeks of each other.
Harvey in 2017 was the wettest tropical cyclone on record in the United States, and most of the damage it did in Houston was flooding. A homeowners policy excludes flood, which needs a separate flood policy, and new flood policies usually have a 30-day waiting period. Wind damage and rain that enters through a wind-damaged roof or window are covered under the homeowners policy. When both happen in one storm, proving which damage came from which is what decides how much is paid.
In May 2024 a derecho blew out windows downtown and brought down trees and power lines across the city, and Beryl followed in July, leaving millions of people without power. Wind claims from storms like these often include roofs, fences, windows and trees on structures, plus interior water damage that follows the opening. Your wind or hurricane deductible may be a percentage of the dwelling limit, so check your declarations page before you estimate what you will be paid.
Closer to the coast, many homes buy wind and hail coverage separately from the Texas Windstorm Insurance Association, which writes in the designated coastal counties, including Galveston and Brazoria and part of Harris County. A TWIA claim follows its own rules and deadlines alongside your homeowners and flood claims, so a single storm can mean three claims with three insurers.
Our Texas office is in Dallas at 1999 Bryan Street, Suite 900. Our Texas line, (713) 487-5167, is a Houston number, and our licensed adjusters inspect properties across the Houston area.
Ask for the decision and any engineering report in writing. Roof and window damage, interior water lines and photos taken during or right after the storm can show what the wind did, which the homeowners policy covers whether or not you have flood insurance.
The Texas Windstorm Insurance Association insures wind and hail damage for properties in the designated coastal counties that cannot get that coverage elsewhere. If you have a TWIA policy, a hurricane claim usually involves it, your homeowners insurer and, if you have one, your flood insurer.
Nothing upfront. We are paid a percentage of what the insurer pays on your claim, and only if we recover money for you. Texas law caps a public adjuster's fee at 10% of the claim settlement, and every public adjuster working in Texas must hold a license from the Texas Department of Insurance.
Real Results
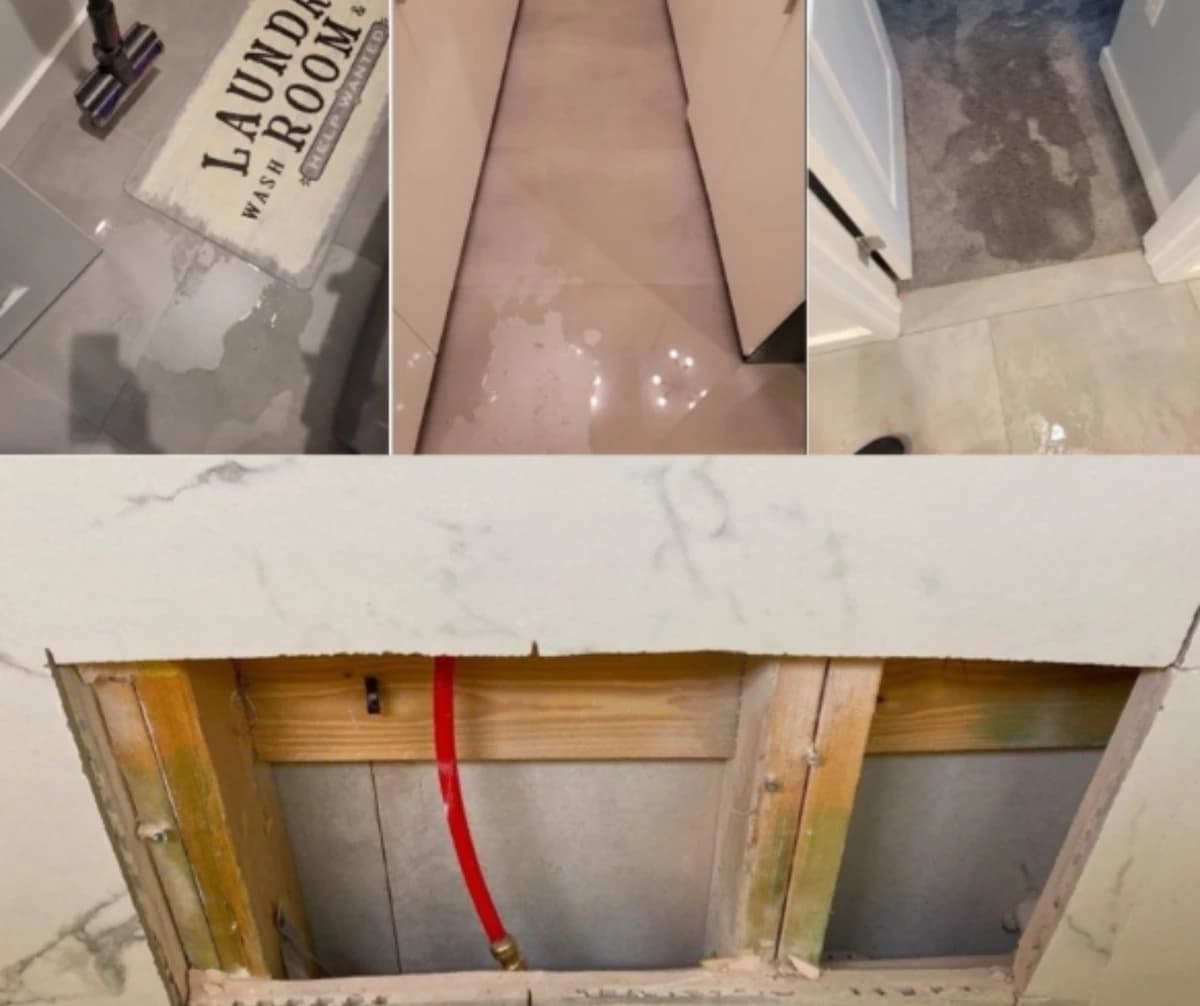
Initial Insurance Offers $9,211
Five Star Result: $82,425
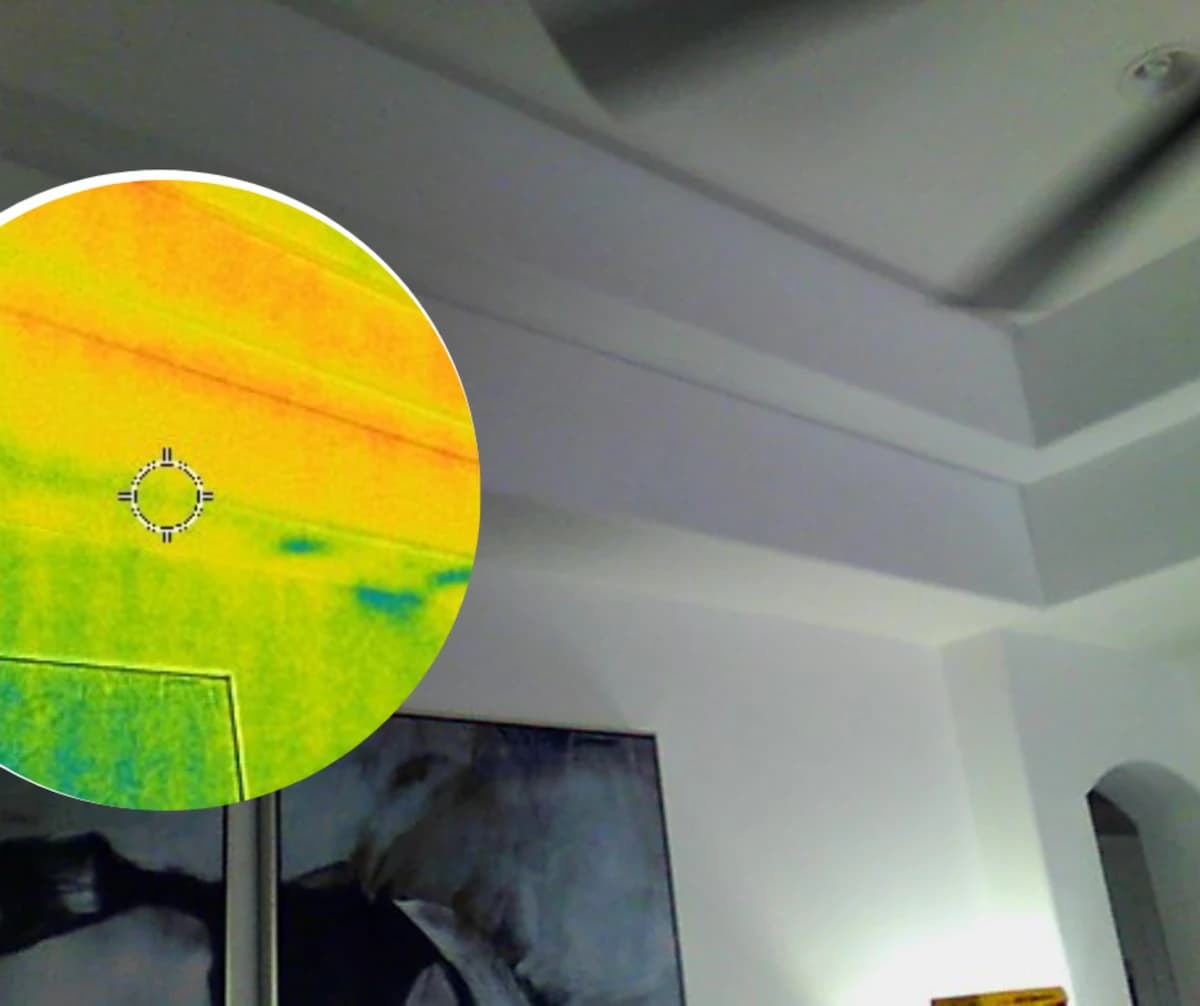
Initial Insurance Offers $20,646
Five Star Result: $147,000
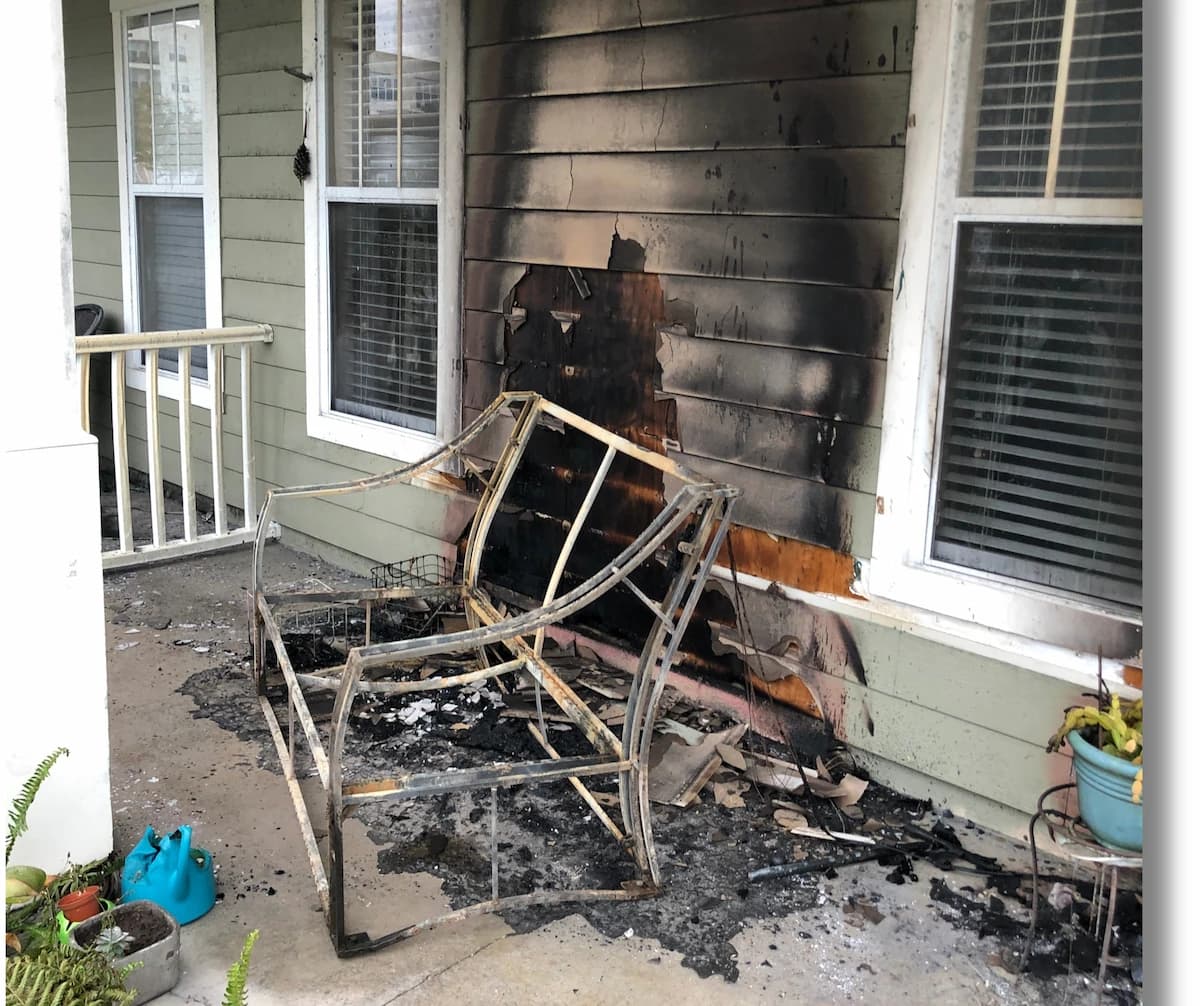
Initial Insurance Offers $19,118
Five Star Result: $37,088
Initial Insurance Offers $740,182
Five Star Result: $2,112,227
Backed by Google Reviews Across Florida
Five Star Claims was super professional and detailed throughout every step of our claim process. They kept us abreast of what was happening at all times and worked extra hard for us! We recommend Five Star 100 percent!
Five Star made a difficult process seamless, painless, and easy. I strongly recommend their services when dealing with difficult insurance claims, and you will be a satisfied client like me.
I had a great experience with Five Star Claims. They are very professional and great communication through the process. A+ company
Thank you for all your help. You made this experience easier. Your commitment to do right by us is admirable. You made sure we understood the process and made sure communication was clear and consistent.
Five Star is truly phenomenal. They handled my claim as if I were a family member. They were courteous, caring, attentive, and communicated through the entire process.
Five Star did a wonderful job handling my claim. I would highly recommend them!
Trustworthy and effective! Five Star Claims Adjusting goes above and beyond.
I had a great experience! Help me with all the questions that I had and solve every problem easily!
The professionalism and honesty were outstanding. Most definitely recommend 5 Star if you are searching.