Flood & Water Damage
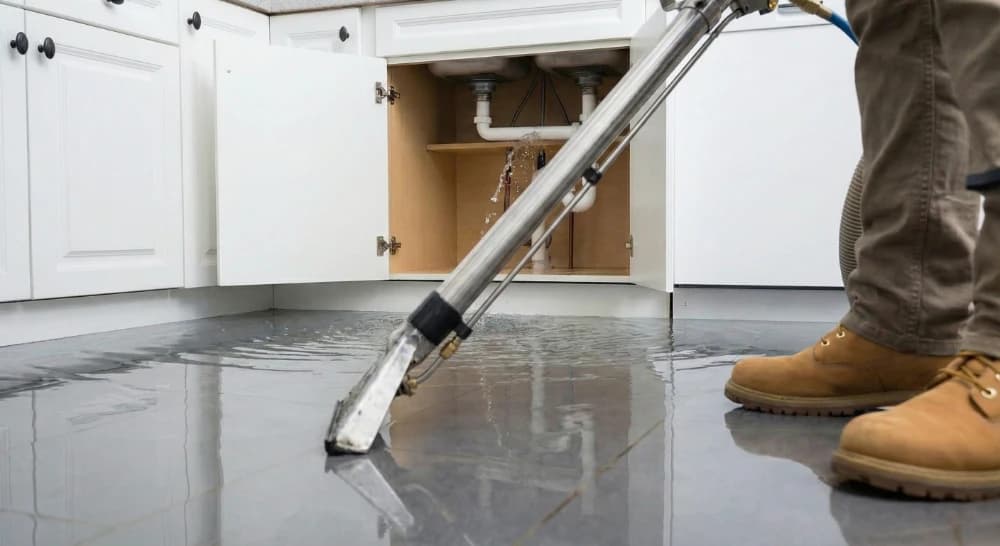
Rainfall flooding, drainage backup and the interior damage that follows. Which policy responds depends on the path the water took — so we document it.
Property Damage in Oakland Park?
Broward County floods in ways the rest of Florida does not — the April 2023 storm dropped roughly two feet of rain on the Fort Lauderdale area in a single day, and plenty of those claims are still disputed. Add flat roofs, ageing condo stock and associations arguing over what is theirs and what is yours, and coverage gets complicated fast. Our licensed public adjusters work from W Oakland Park Blvd.
Call Our Broward Team: (954) 302-1106
Insurance companies have a team working to minimize what they pay you. You deserve the same expertise on your side.
Five Star’s public adjusters step in immediately after a loss to manage every aspect of your claim — from documentation to negotiation — so nothing gets left on the table.
Broward claims tend to turn on two things: where the water came from, and whose property the damage sits on. Both are answerable, and both are worth money.
Rainfall flooding, drainage backup and the interior damage that follows. Which policy responds depends on the path the water took — so we document it.
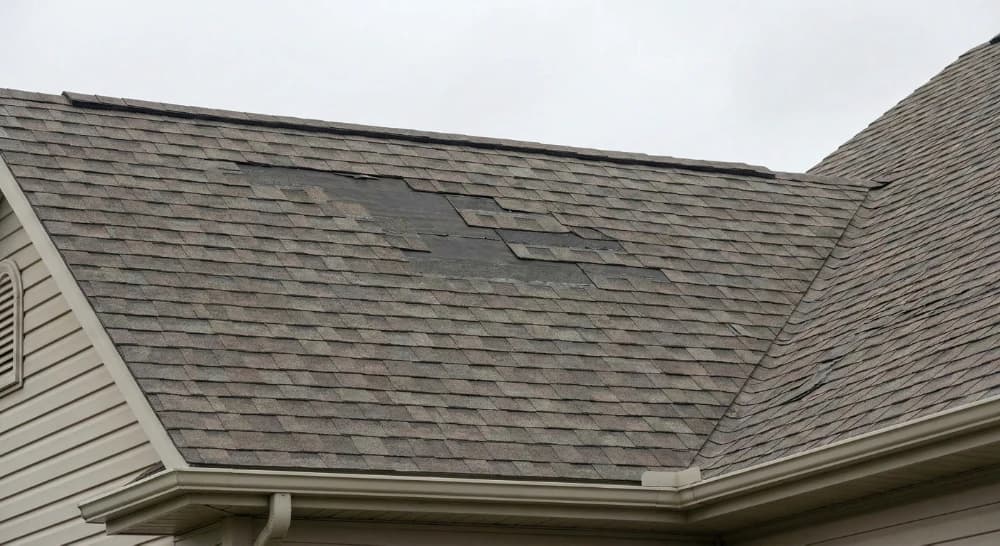
Flat and low-slope roofs fail differently from pitched ones, and are more often written off as wear rather than storm damage. That distinction is worth arguing.
Our South Florida office is on W Oakland Park Blvd, so Oakland Park claims are the ones closest to home. Much of the city's housing went up in the decades after the war: single-story block homes, low-slope roofs and plumbing that is now fifty or more years old. That shapes the claims we handle here more than any one storm does.
Homes of this age often still drain through cast iron pipes under the slab. When they fail, the water damage that follows is frequently covered even though the corroded pipe itself is not, and many policies also pay to tear out and replace the floor or slab needed to reach the leak. Insurers often push back by calling the leak long-term seepage or wear and tear, so when the damage was discovered and what the plumber's camera inspection shows both matter. Supply-line, water heater and AC drain-line leaks follow the same pattern.
Flat and low-slope roofs are common here, and insurers are quick to call their failures age or maintenance rather than storm damage. Wind can lift membrane edges and flashing without leaving anything obvious from the street, and the interior water damage that follows is then paid as if it had no storm cause. We document the roof and the interior together so the cause is established once.
The April 2023 storm flooded streets across Oakland Park as well as Fort Lauderdale. Homeowners policies exclude flood, which needs a separate flood policy, and they also exclude water that backs up through drains and sewers unless you added a water backup endorsement. Which of those covers your damage depends on the path the water took, and that is a question of evidence.
Our South Florida office is at 1640 W Oakland Park Blvd #202, Oakland Park, FL 33311, and the team there answers on (954) 302-1106. We inspect at your property, so you don't need to come in.
Not necessarily. The pipe itself is usually excluded, but sudden water damage that resulted from it and the cost of reaching the pipe are often covered. Ask for the denial in writing with the policy language it relies on, and keep the plumber's camera video. Our guide to cast iron pipe claims explains how these claims are decided.
Yes. In a condo, the association's master policy and your unit-owner policy each cover different parts of the same damage. We work out which policy owes what and pursue each one.
Nothing upfront. We are paid a percentage of what the insurer pays on your claim, and only if we recover money for you. Florida law caps public adjuster fees at 20% of the claim payment, and at 10% for claims from a declared state of emergency during the first year after the event.
Real Results
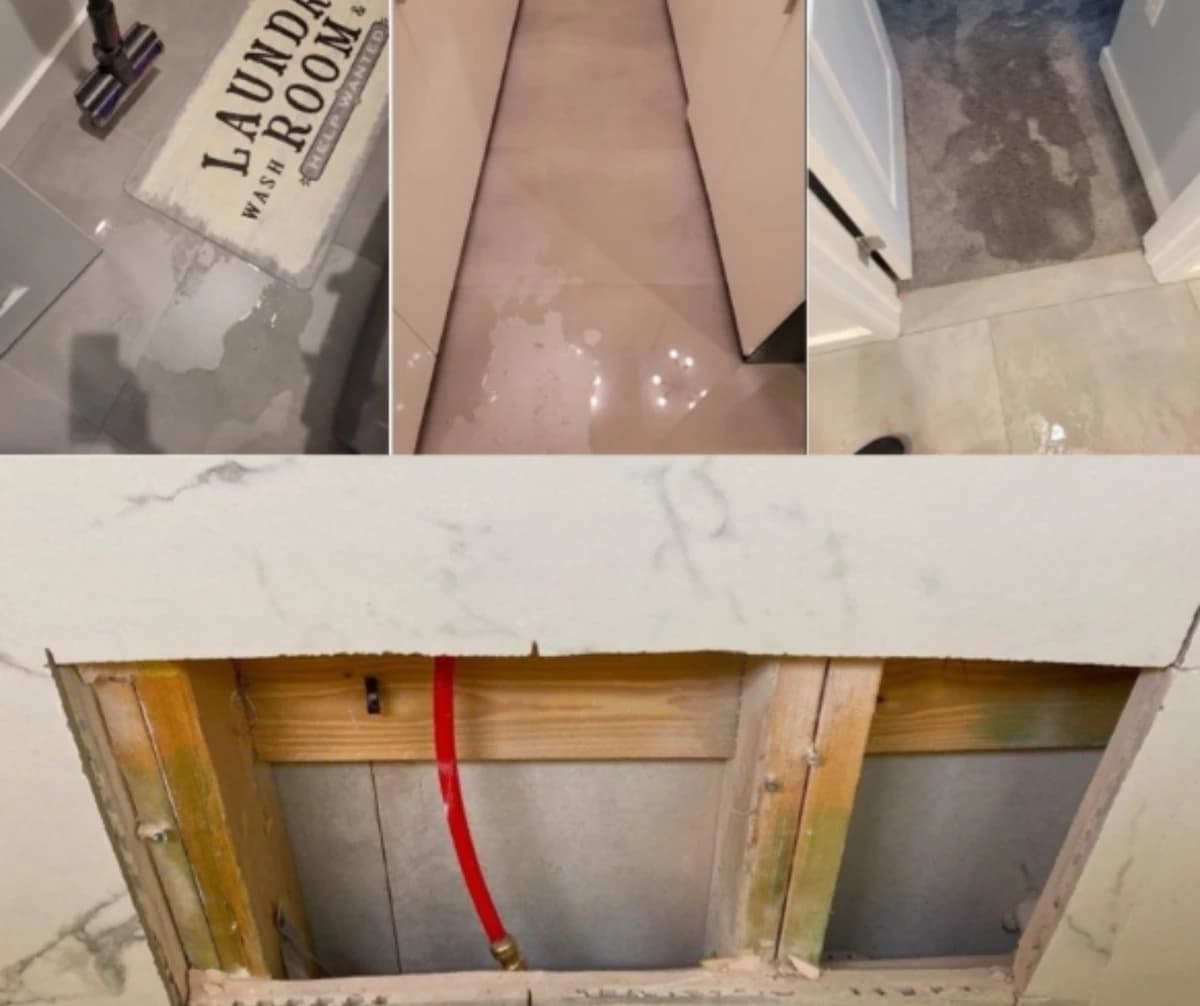
Initial Insurance Offers $9,211
Five Star Result: $82,425
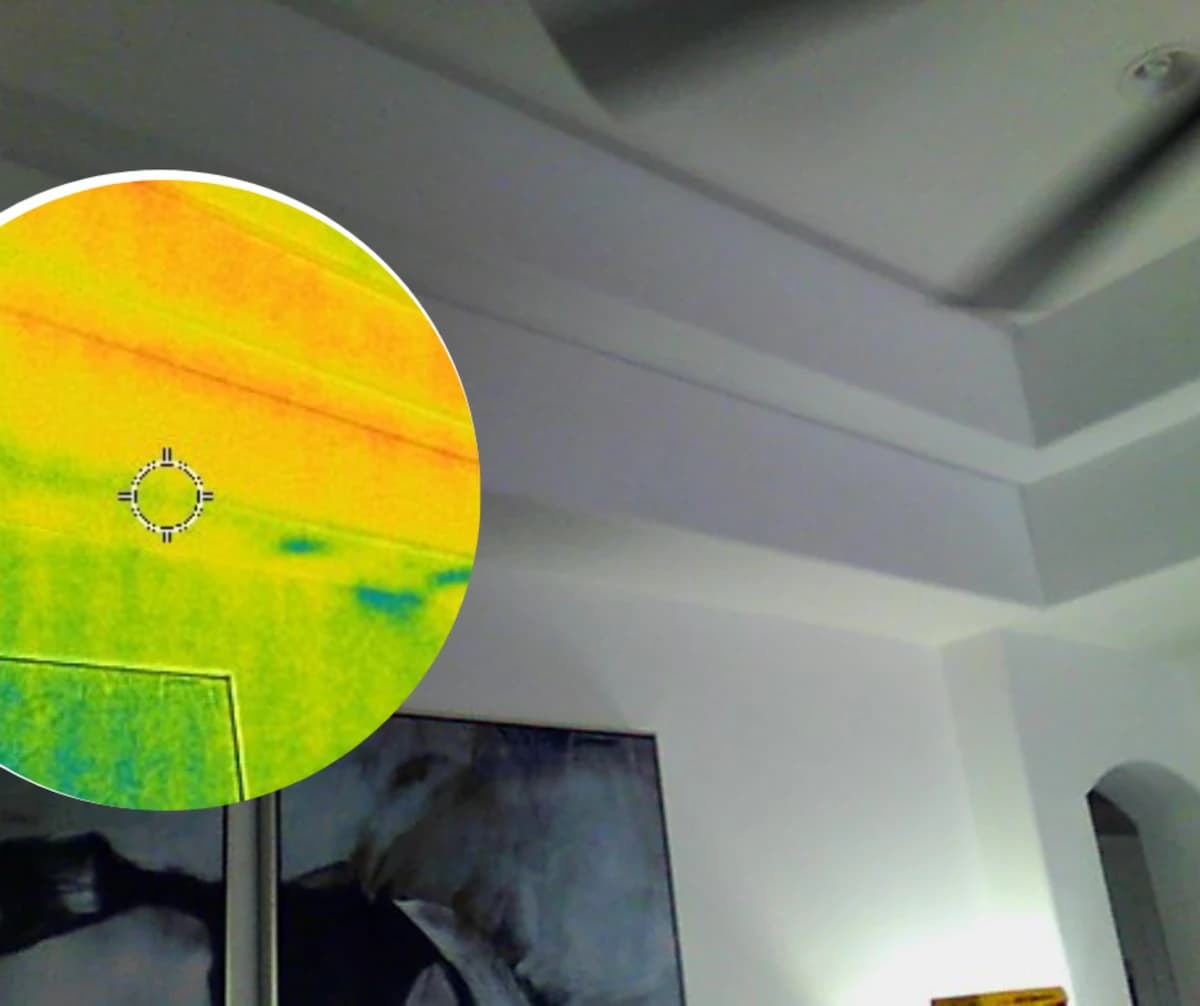
Initial Insurance Offers $20,646
Five Star Result: $147,000
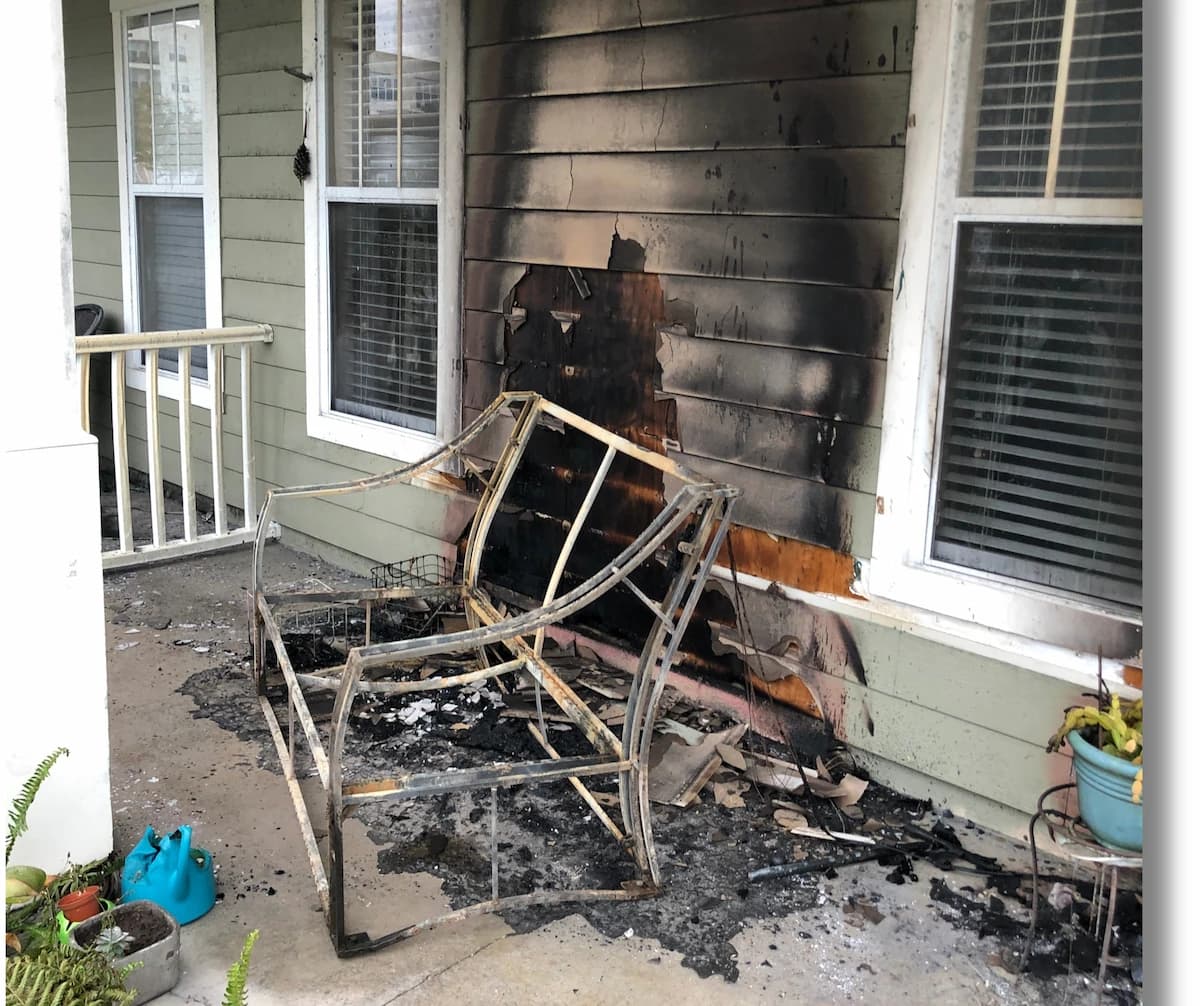
Initial Insurance Offers $19,118
Five Star Result: $37,088
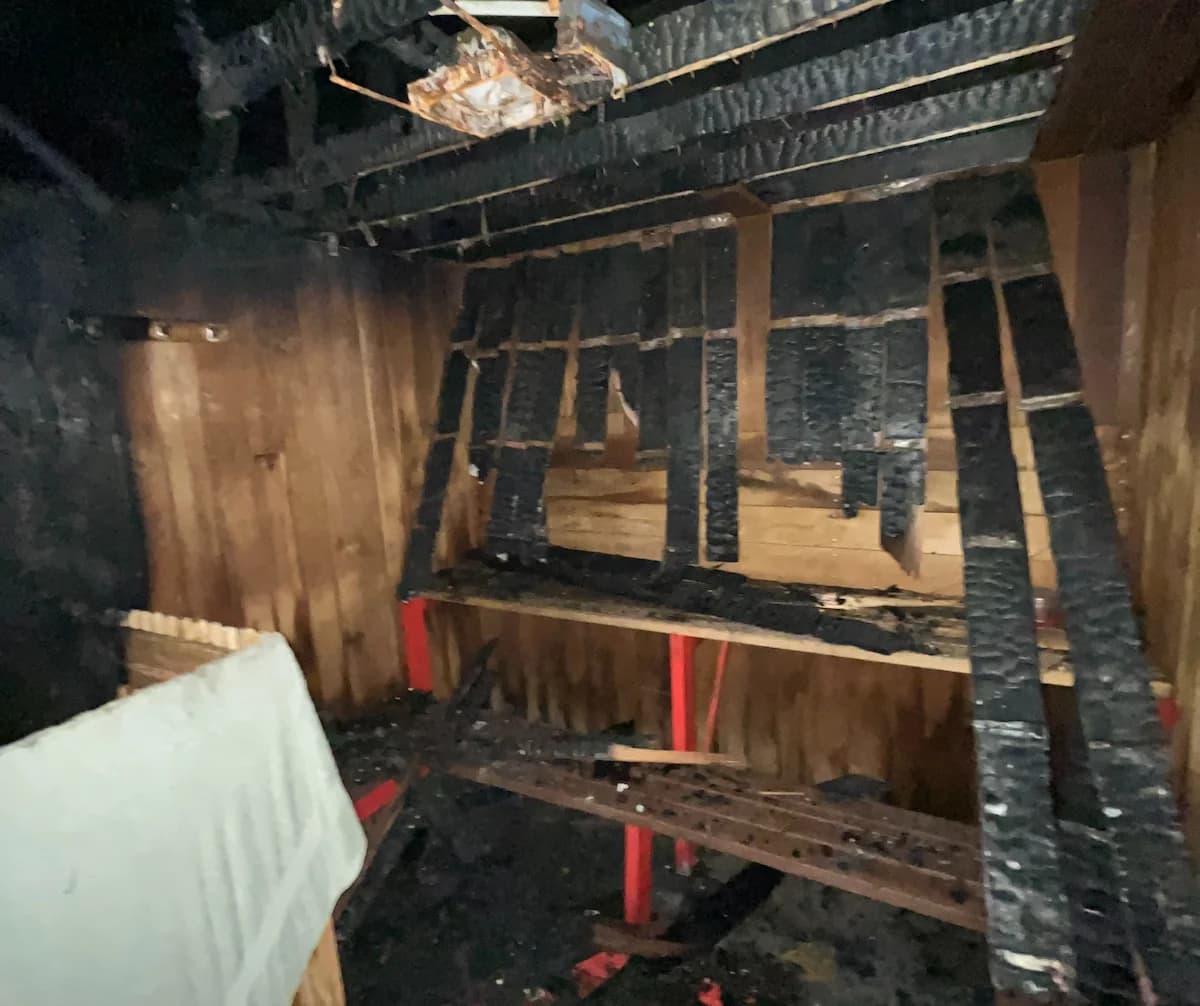
Initial Insurance Offers $740,182
Five Star Result: $2,112,227
Backed by Google Reviews Across Florida
Five Star Claims was super professional and detailed throughout every step of our claim process. They kept us abreast of what was happening at all times and worked extra hard for us! We recommend Five Star 100 percent!
Five Star made a difficult process seamless, painless, and easy. I strongly recommend their services when dealing with difficult insurance claims, and you will be a satisfied client like me.
I had a great experience with Five Star Claims. They are very professional and great communication through the process. A+ company
Thank you for all your help. You made this experience easier. Your commitment to do right by us is admirable. You made sure we understood the process and made sure communication was clear and consistent.
Five Star is truly phenomenal. They handled my claim as if I were a family member. They were courteous, caring, attentive, and communicated through the entire process.
Five Star did a wonderful job handling my claim. I would highly recommend them!
Trustworthy and effective! Five Star Claims Adjusting goes above and beyond.
I had a great experience! Help me with all the questions that I had and solve every problem easily!
The professionalism and honesty were outstanding. Most definitely recommend 5 Star if you are searching.