Hurricane & Wind Damage
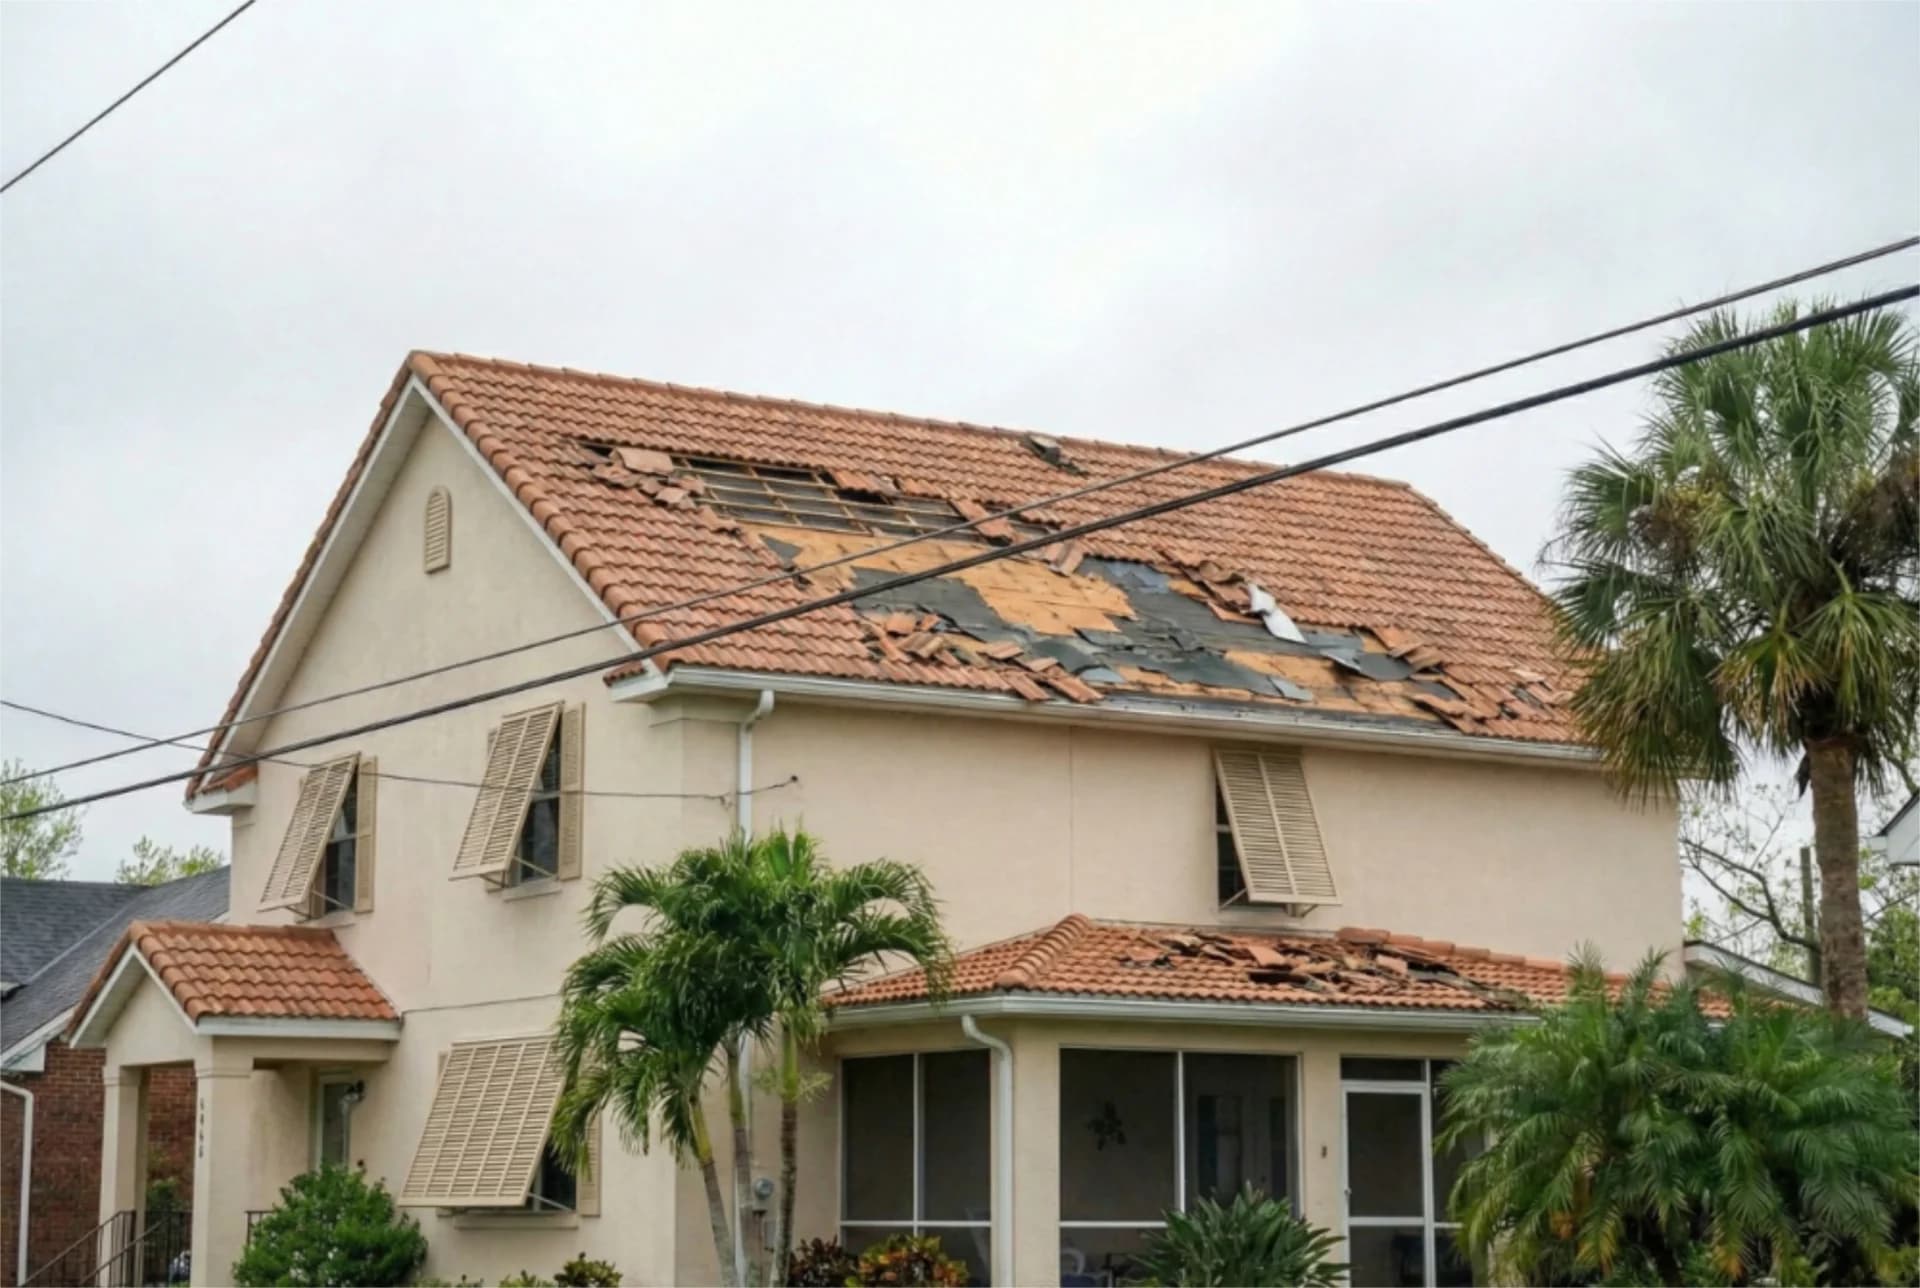
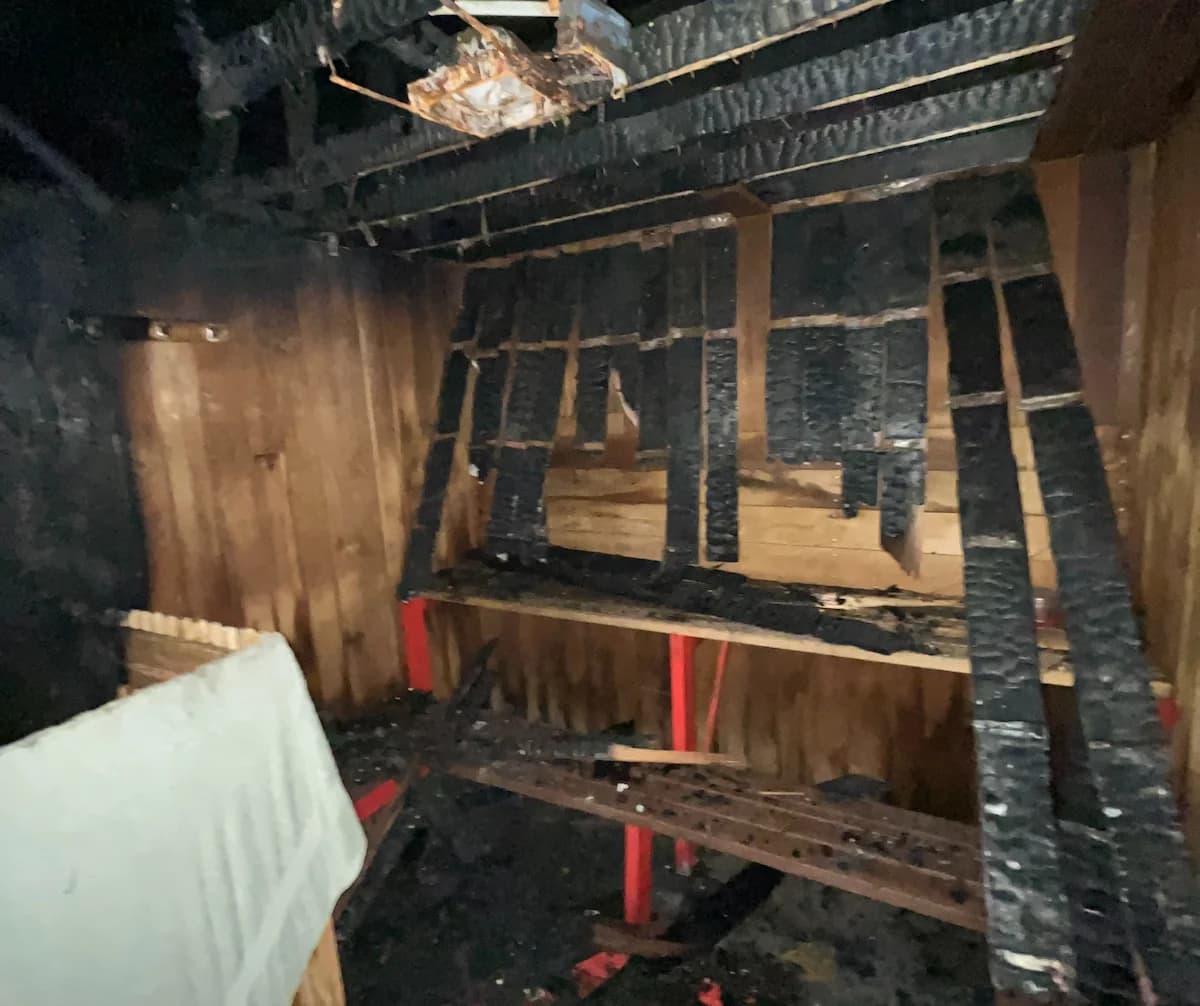
Roof, window, fence and screen enclosure damage from Isaias's winds, documented slope by slope and opening by opening.
Hurricane Isaias
Hurricane Isaias is bearing down on the Florida Panhandle. Five Star's licensed Florida public adjusters help homeowners and businesses document wind, rain and storm damage and get the claim paid in full. No upfront cost, and fees on Isaias claims are capped at 10% under Florida's emergency rules.
Call Five Star: 888-578-2735
Hurricane Isaias is forecast to make landfall on the northern Gulf Coast late Friday, October 9, or early Saturday, October 10, 2026. As of the National Hurricane Center's 7 a.m. CDT advisory on October 8, a hurricane warning covers the Florida Panhandle west of the Bay/Gulf county line, which includes Pensacola, Navarre, Fort Walton Beach, Destin and Panama City, and a storm surge warning runs along the coast to the Steinhatchee River. Follow the National Hurricane Center and your county emergency management office for the latest track and evacuation orders. Your safety comes before any insurance claim.
If you have time and it is safe, walk through your home and record a video of every room, the roof as seen from the ground, the exterior on every side, and your major belongings. Photos taken before the storm are the best evidence you will ever have of your property's condition. Put your insurance policy, declarations page and photos somewhere you can reach from your phone, and note your hurricane deductible, which in Florida is usually a percentage of the dwelling limit rather than a flat amount.
Once it is safe, photograph and video all damage before you move or throw anything away, including roofs, ceilings, windows, fences, screen enclosures and soaked flooring and furniture. Make only the temporary repairs needed to stop further damage, such as tarping the roof and boarding windows, and keep every receipt, because reasonable emergency repairs are part of the claim. Report the claim to your insurer promptly. Be cautious of anyone who asks you to sign over your insurance benefits or pressures you to sign a repair contract on the spot.
Homeowners insurance covers wind damage, and rain that enters through an opening the wind created, subject to your hurricane deductible. It does not cover flooding or storm surge, which need a separate flood policy. When a home takes both wind and water, the insurer will look closely at which caused what. Documenting the roof, window and wall damage separately from the water line is how the wind portion of the claim gets paid in full.
Governor DeSantis declared a state of emergency on October 6, 2026, for 25 counties in the Panhandle and Big Bend, including Escambia, Santa Rosa, Okaloosa, Walton and Bay. Under Florida law, a public adjuster's fee on claims from a declared emergency is capped at 10% of the claim payment for claims made during the year after the declaration, half the normal cap, and you can cancel a public adjuster contract for an emergency claim without penalty within 30 days of the loss. Five Star's licensed Florida public adjusters charge nothing upfront and are paid only if we recover money for you.
THIS IS A SOLICITATION FOR BUSINESS. IF YOU HAVE HAD A CLAIM FOR AN INSURED PROPERTY LOSS OR DAMAGE AND YOU ARE SATISFIED WITH THE PAYMENT BY YOUR INSURER, YOU MAY DISREGARD THIS ADVERTISEMENT.
Yes. Our licensed Florida public adjusters handle hurricane claims across Florida, including Escambia, Santa Rosa, Okaloosa, Walton and Bay counties. Request a free claim review on this page or call 888-578-2735, and we will arrange an inspection once it is safe.
Nothing upfront. Because Isaias is the subject of a declared state of emergency in Florida, a public adjuster's fee on claims from the storm is capped by law at 10% of the claim payment for claims made in the year after the declaration.
No. Homeowners policies exclude flooding and storm surge, which are covered only by a flood policy. Wind damage, and rain that came in through openings the wind created, are covered by your homeowners policy, so it is important to document them separately.
Florida law generally requires notice of a new property claim within one year of the date of loss, and a supplemental claim within 18 months. Report it as soon as you can, because evidence is easiest to gather right after the storm.
A hurricane claim is several claims at once: the roof, the water that came in behind it, and everything inside. Each is documented on its own so none of it is left out.
Roof, window, fence and screen enclosure damage from Isaias's winds, documented slope by slope and opening by opening.
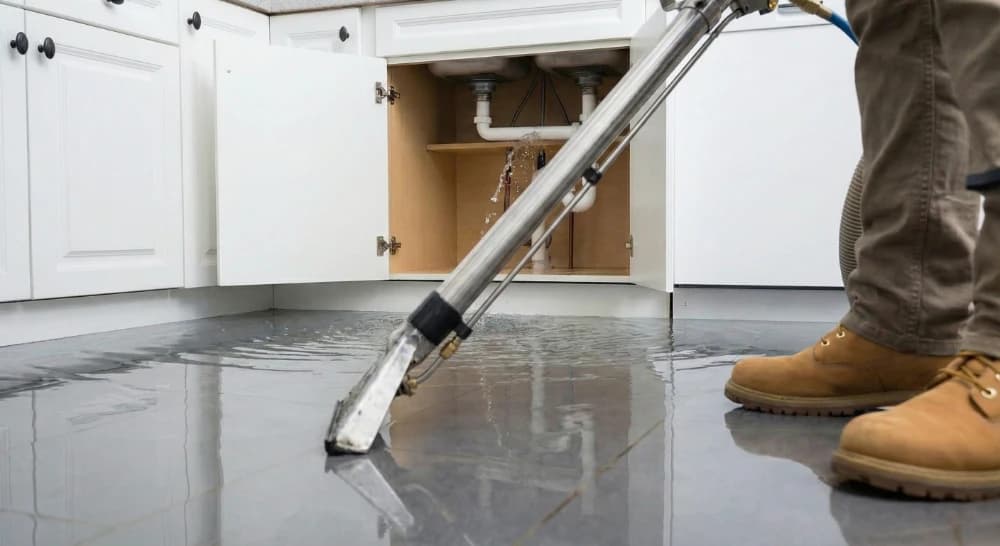
Rain that entered through wind damage is covered under your homeowners policy. We prove the path the water took.
Real Results
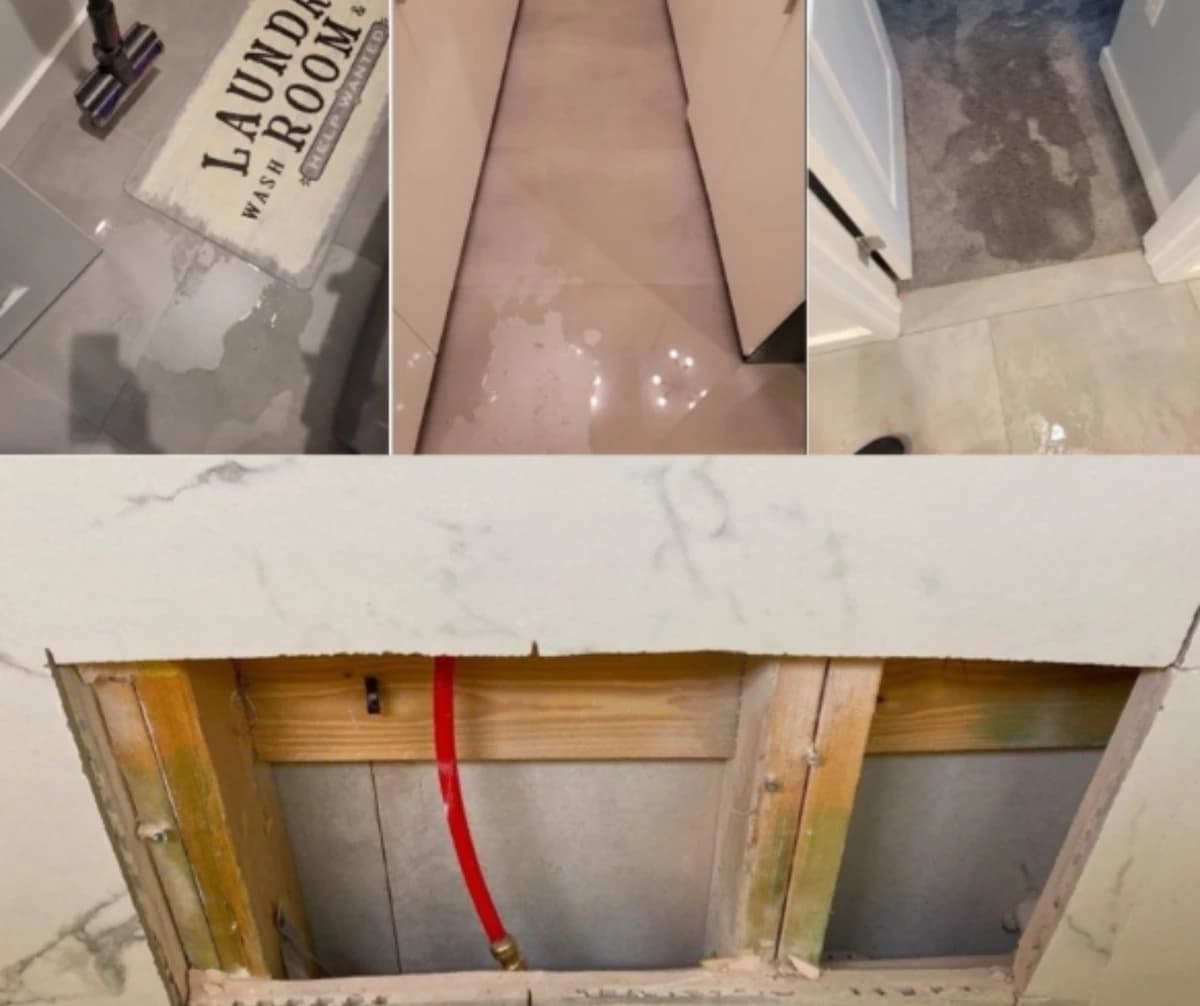
Initial Insurance Offers $9,211
Five Star Result: $82,425
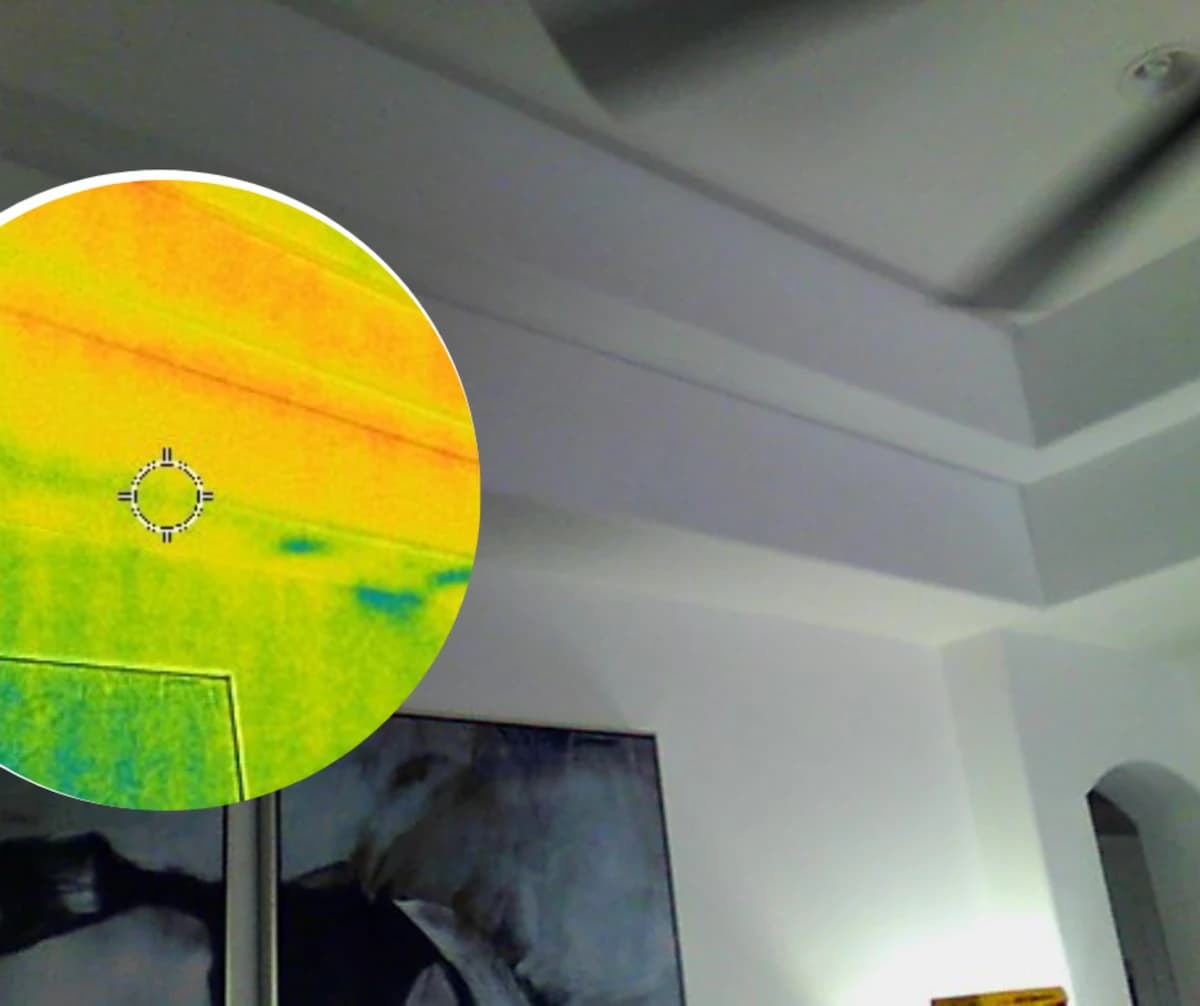
Initial Insurance Offers $20,646
Five Star Result: $147,000
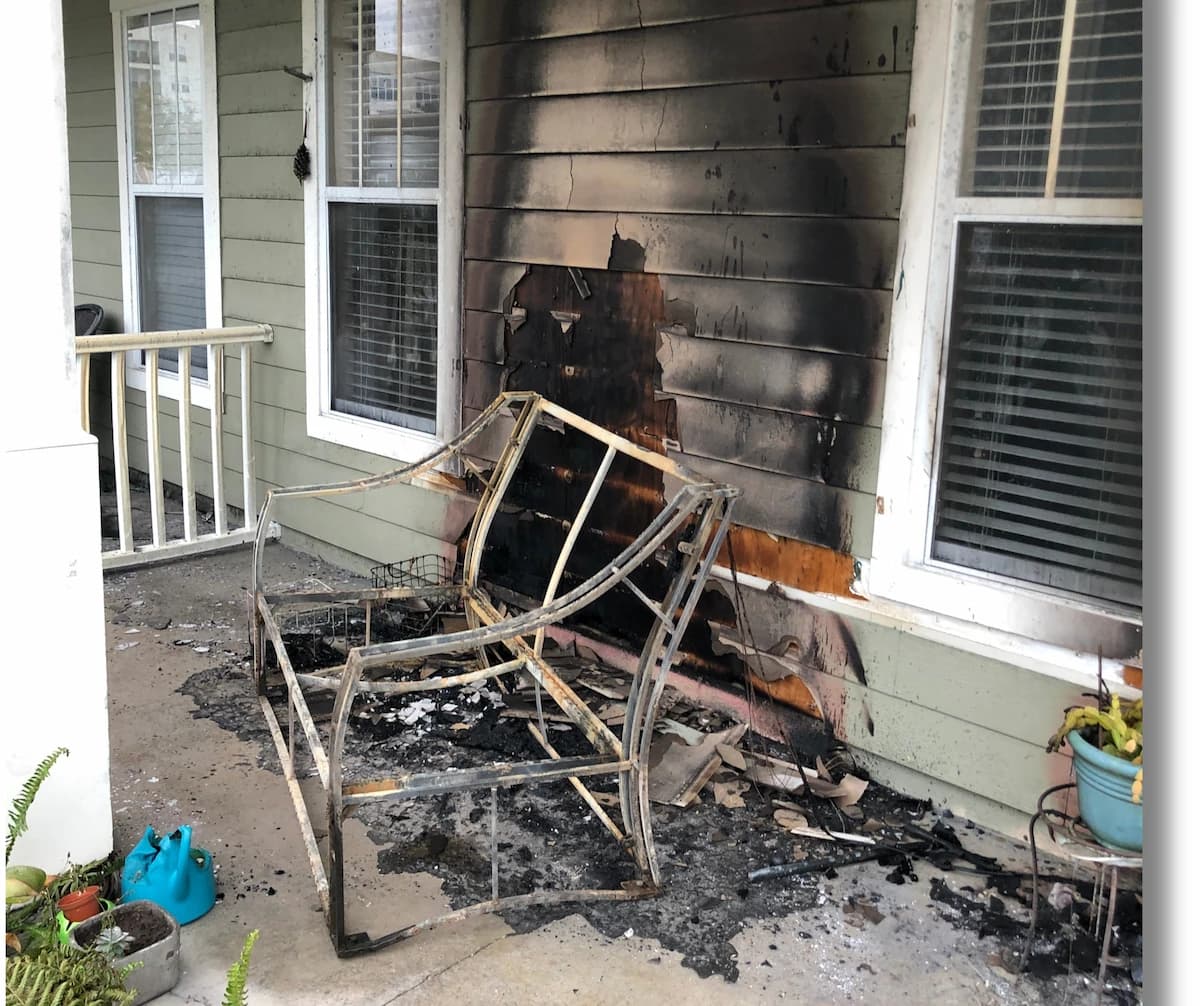
Initial Insurance Offers $19,118
Five Star Result: $37,088
Initial Insurance Offers $740,182
Five Star Result: $2,112,227
Backed by Google Reviews Across Florida
Five Star Claims was super professional and detailed throughout every step of our claim process. They kept us abreast of what was happening at all times and worked extra hard for us! We recommend Five Star 100 percent!
Five Star made a difficult process seamless, painless, and easy. I strongly recommend their services when dealing with difficult insurance claims, and you will be a satisfied client like me.
I had a great experience with Five Star Claims. They are very professional and great communication through the process. A+ company
Thank you for all your help. You made this experience easier. Your commitment to do right by us is admirable. You made sure we understood the process and made sure communication was clear and consistent.
Five Star is truly phenomenal. They handled my claim as if I were a family member. They were courteous, caring, attentive, and communicated through the entire process.
Five Star did a wonderful job handling my claim. I would highly recommend them!
Trustworthy and effective! Five Star Claims Adjusting goes above and beyond.
I had a great experience! Help me with all the questions that I had and solve every problem easily!
The professionalism and honesty were outstanding. Most definitely recommend 5 Star if you are searching.